Auteur
Jonathan Hobbs, CFA
Date
14 Oct 2026
Catégorie
Market Insights
How Options Can Earn Monthly Income From Oil
Votre capital est exposé à un risque si vous investissez. Vous pouvez perdre la totalité de votre investissement. Veuillez consulter l’avertissement complet sur les risques ici
West Texas Intermediate (WTI) crude oil traded above $100 a barrel in September, and is up around 60% year-to-date. But as a commodity investment, oil pays no income – however high the price goes. This article explains how the IncomeShares WTI Oil+ Yield ETP (an exchange-traded product) aims to earn income from oil. It then shows how that strategy has performed since we launched it five months ago.
How investors can get exposure to oil
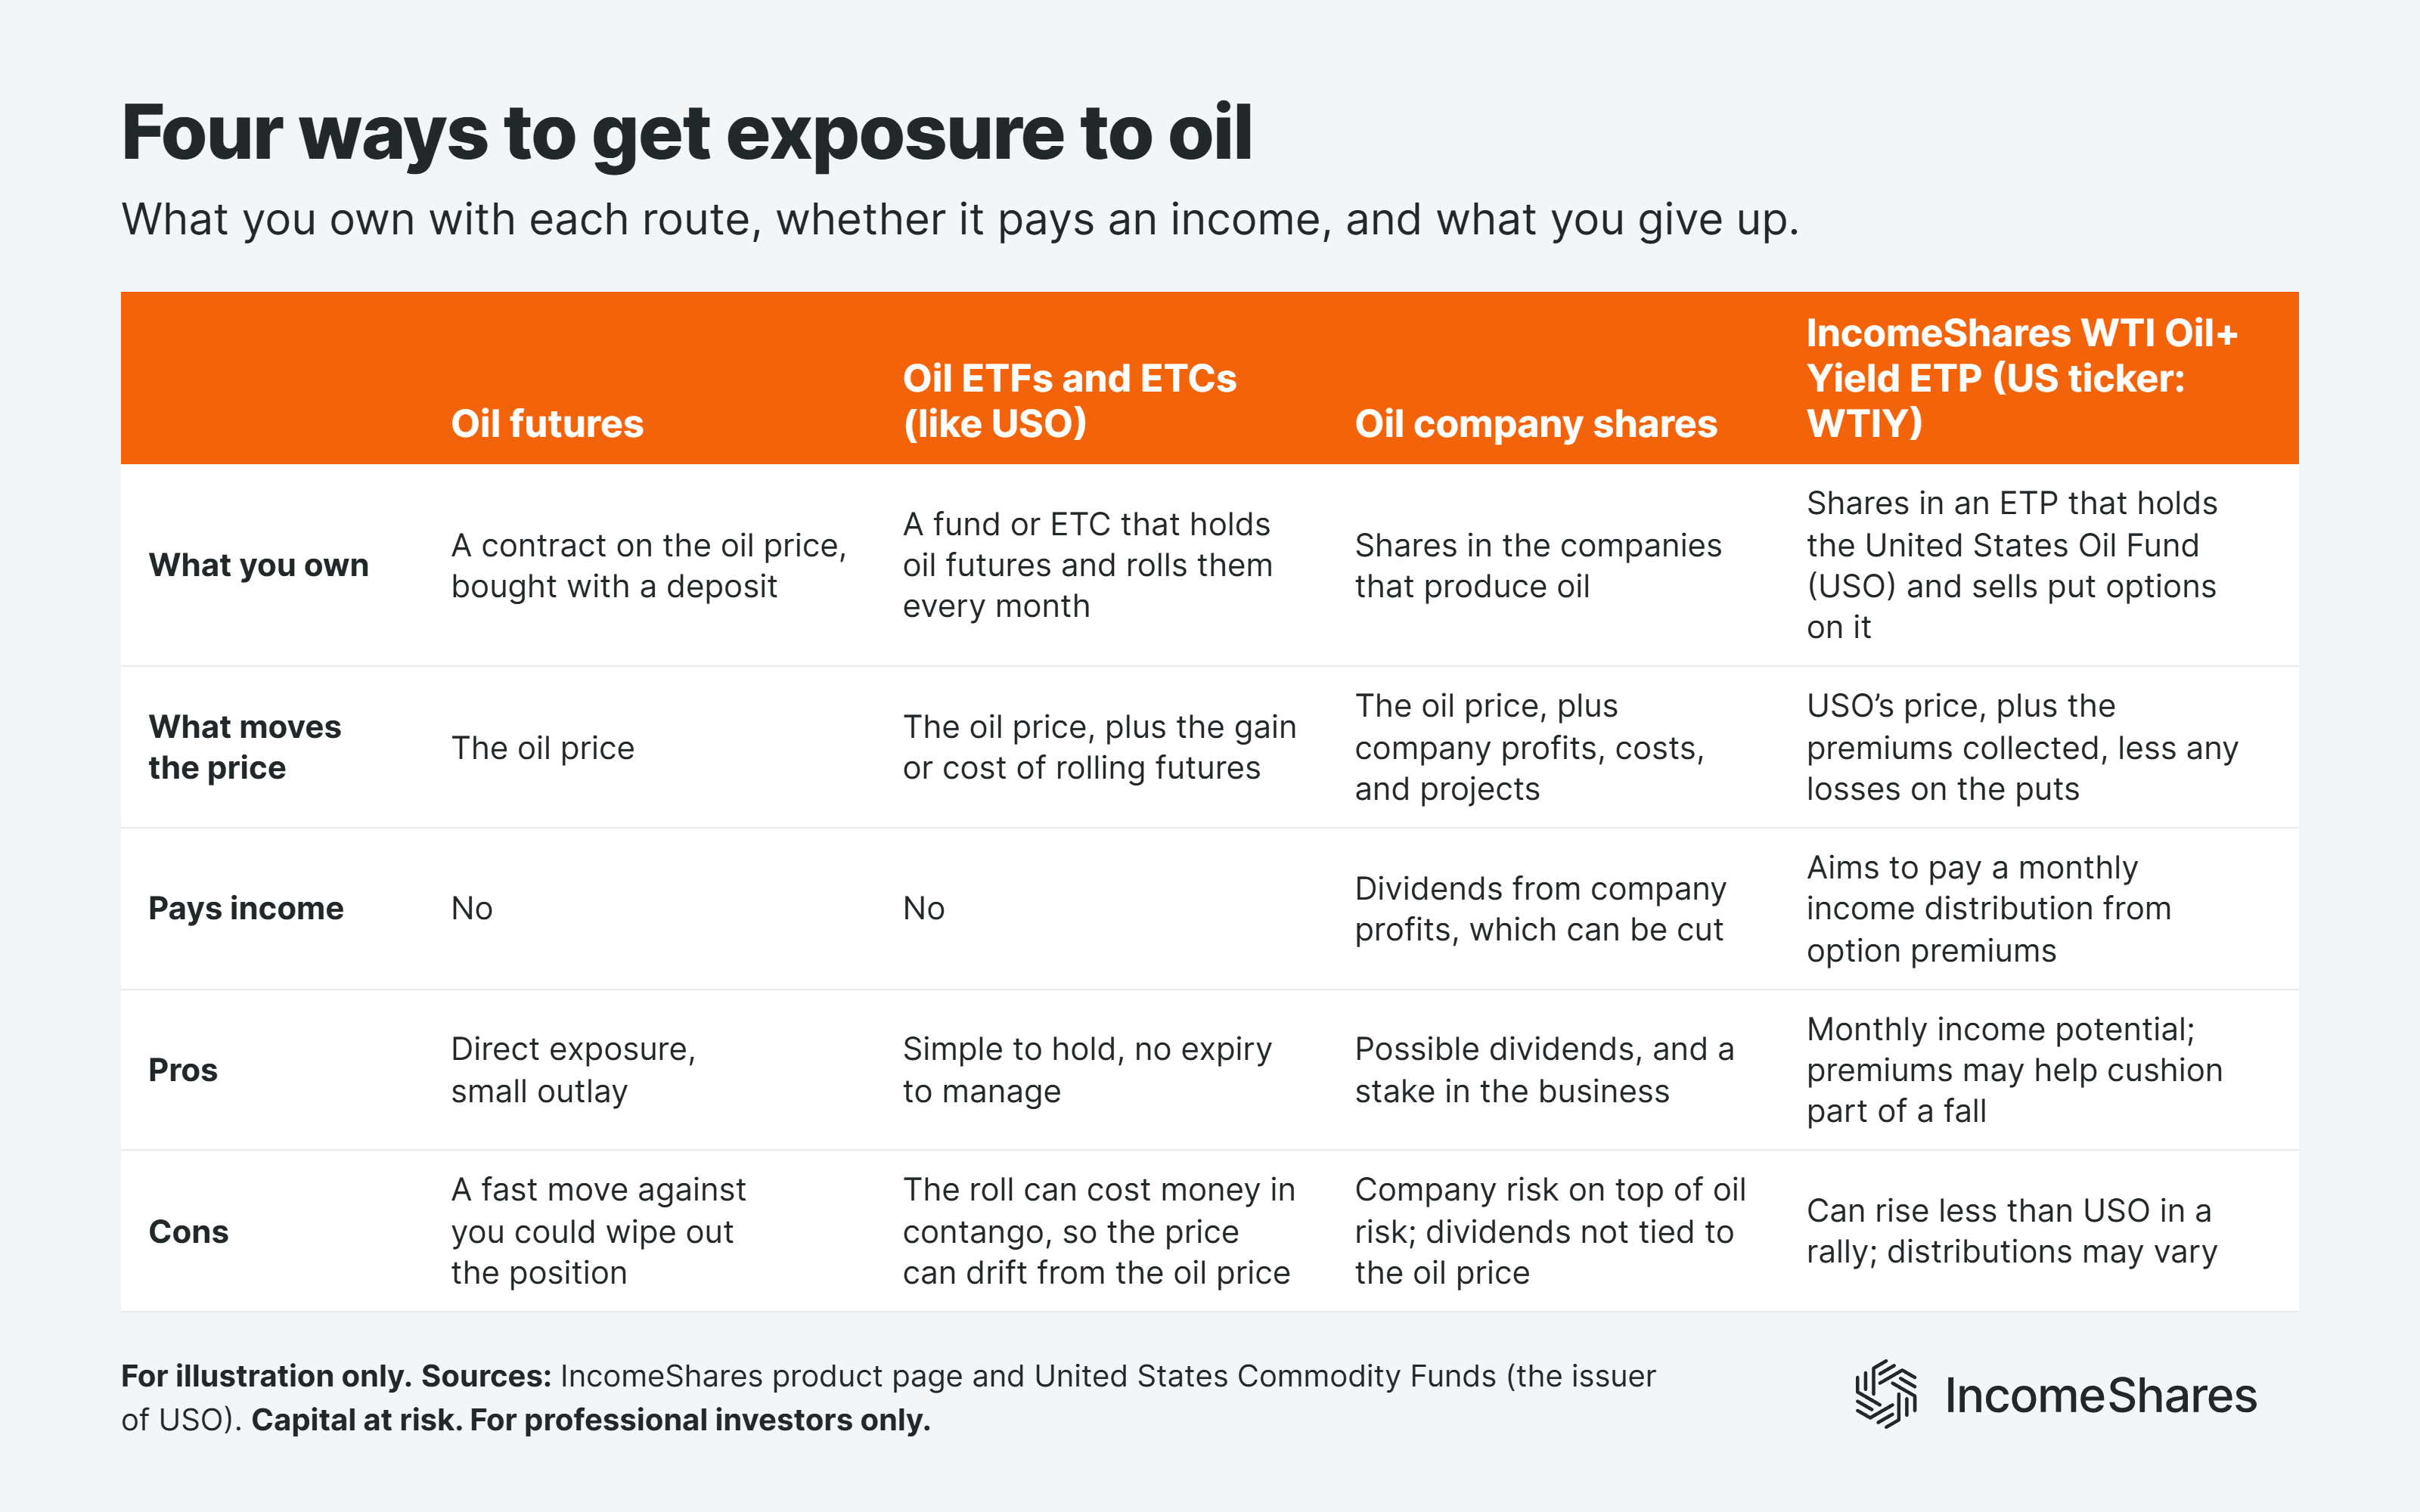
There are a few ways investors can get exposure to the oil price. Only the last two could pay an income.
Oil futures. A futures contract is an agreement to buy oil at a set price on a set date. You only put down a deposit (margin), so gains and losses can be more than the money you invest. A fast move against you could wipe out the position.
Oil ETFs and ETCs. These products hold oil futures for you. In the US, they’re exchange-traded funds (ETFs), like the United States Oil Fund (USO). In the UK and Europe, they’re exchange-traded commodities (ETCs), which are debt securities linked to oil futures. Both typically “roll” those futures every month, so the price can drift away from the actual oil price over time. Some are also leveraged – aiming to move two or three times as much as oil each day.
Oil company shares. You can also buy shares in companies that produce oil, like Shell or Exxon. These may pay dividends, which is one way to potentially earn income from oil. But you’re buying shares in an oil business. That means the share price and dividends will depend on how that business is doing.
Options income ETPs. Our WTI Oil+ Yield ETP (USD ticker: WTIY) holds USO shares and sells put options on USO. The option buyers pay us a fee up front, called a premium. That’s how it aims to earn income from oil. But the ETP holds only part of its exposure in shares, so it can lag USO in a rally. The table below sums up the four investments.
How the WTI Oil+ Yield ETP aims to earn income from oil
Our ETP sells put options on USO. We also set aside enough cash to buy more USO shares if needed (cash-secured put). A put option gives its buyer the right to sell us USO shares at a set strike price.
If USO falls below the strike price: we may have to buy more USO shares at the strike price (using the cash). That strike price would be above the market price of the shares. But the premiums we collect from selling options may help offset that difference.
If USO stays above the strike price: the puts expire “worthless” to the option buyer. Then we don’t need to buy more USO shares.
Either way, the premium goes towards the monthly income distributions we aim to pay.
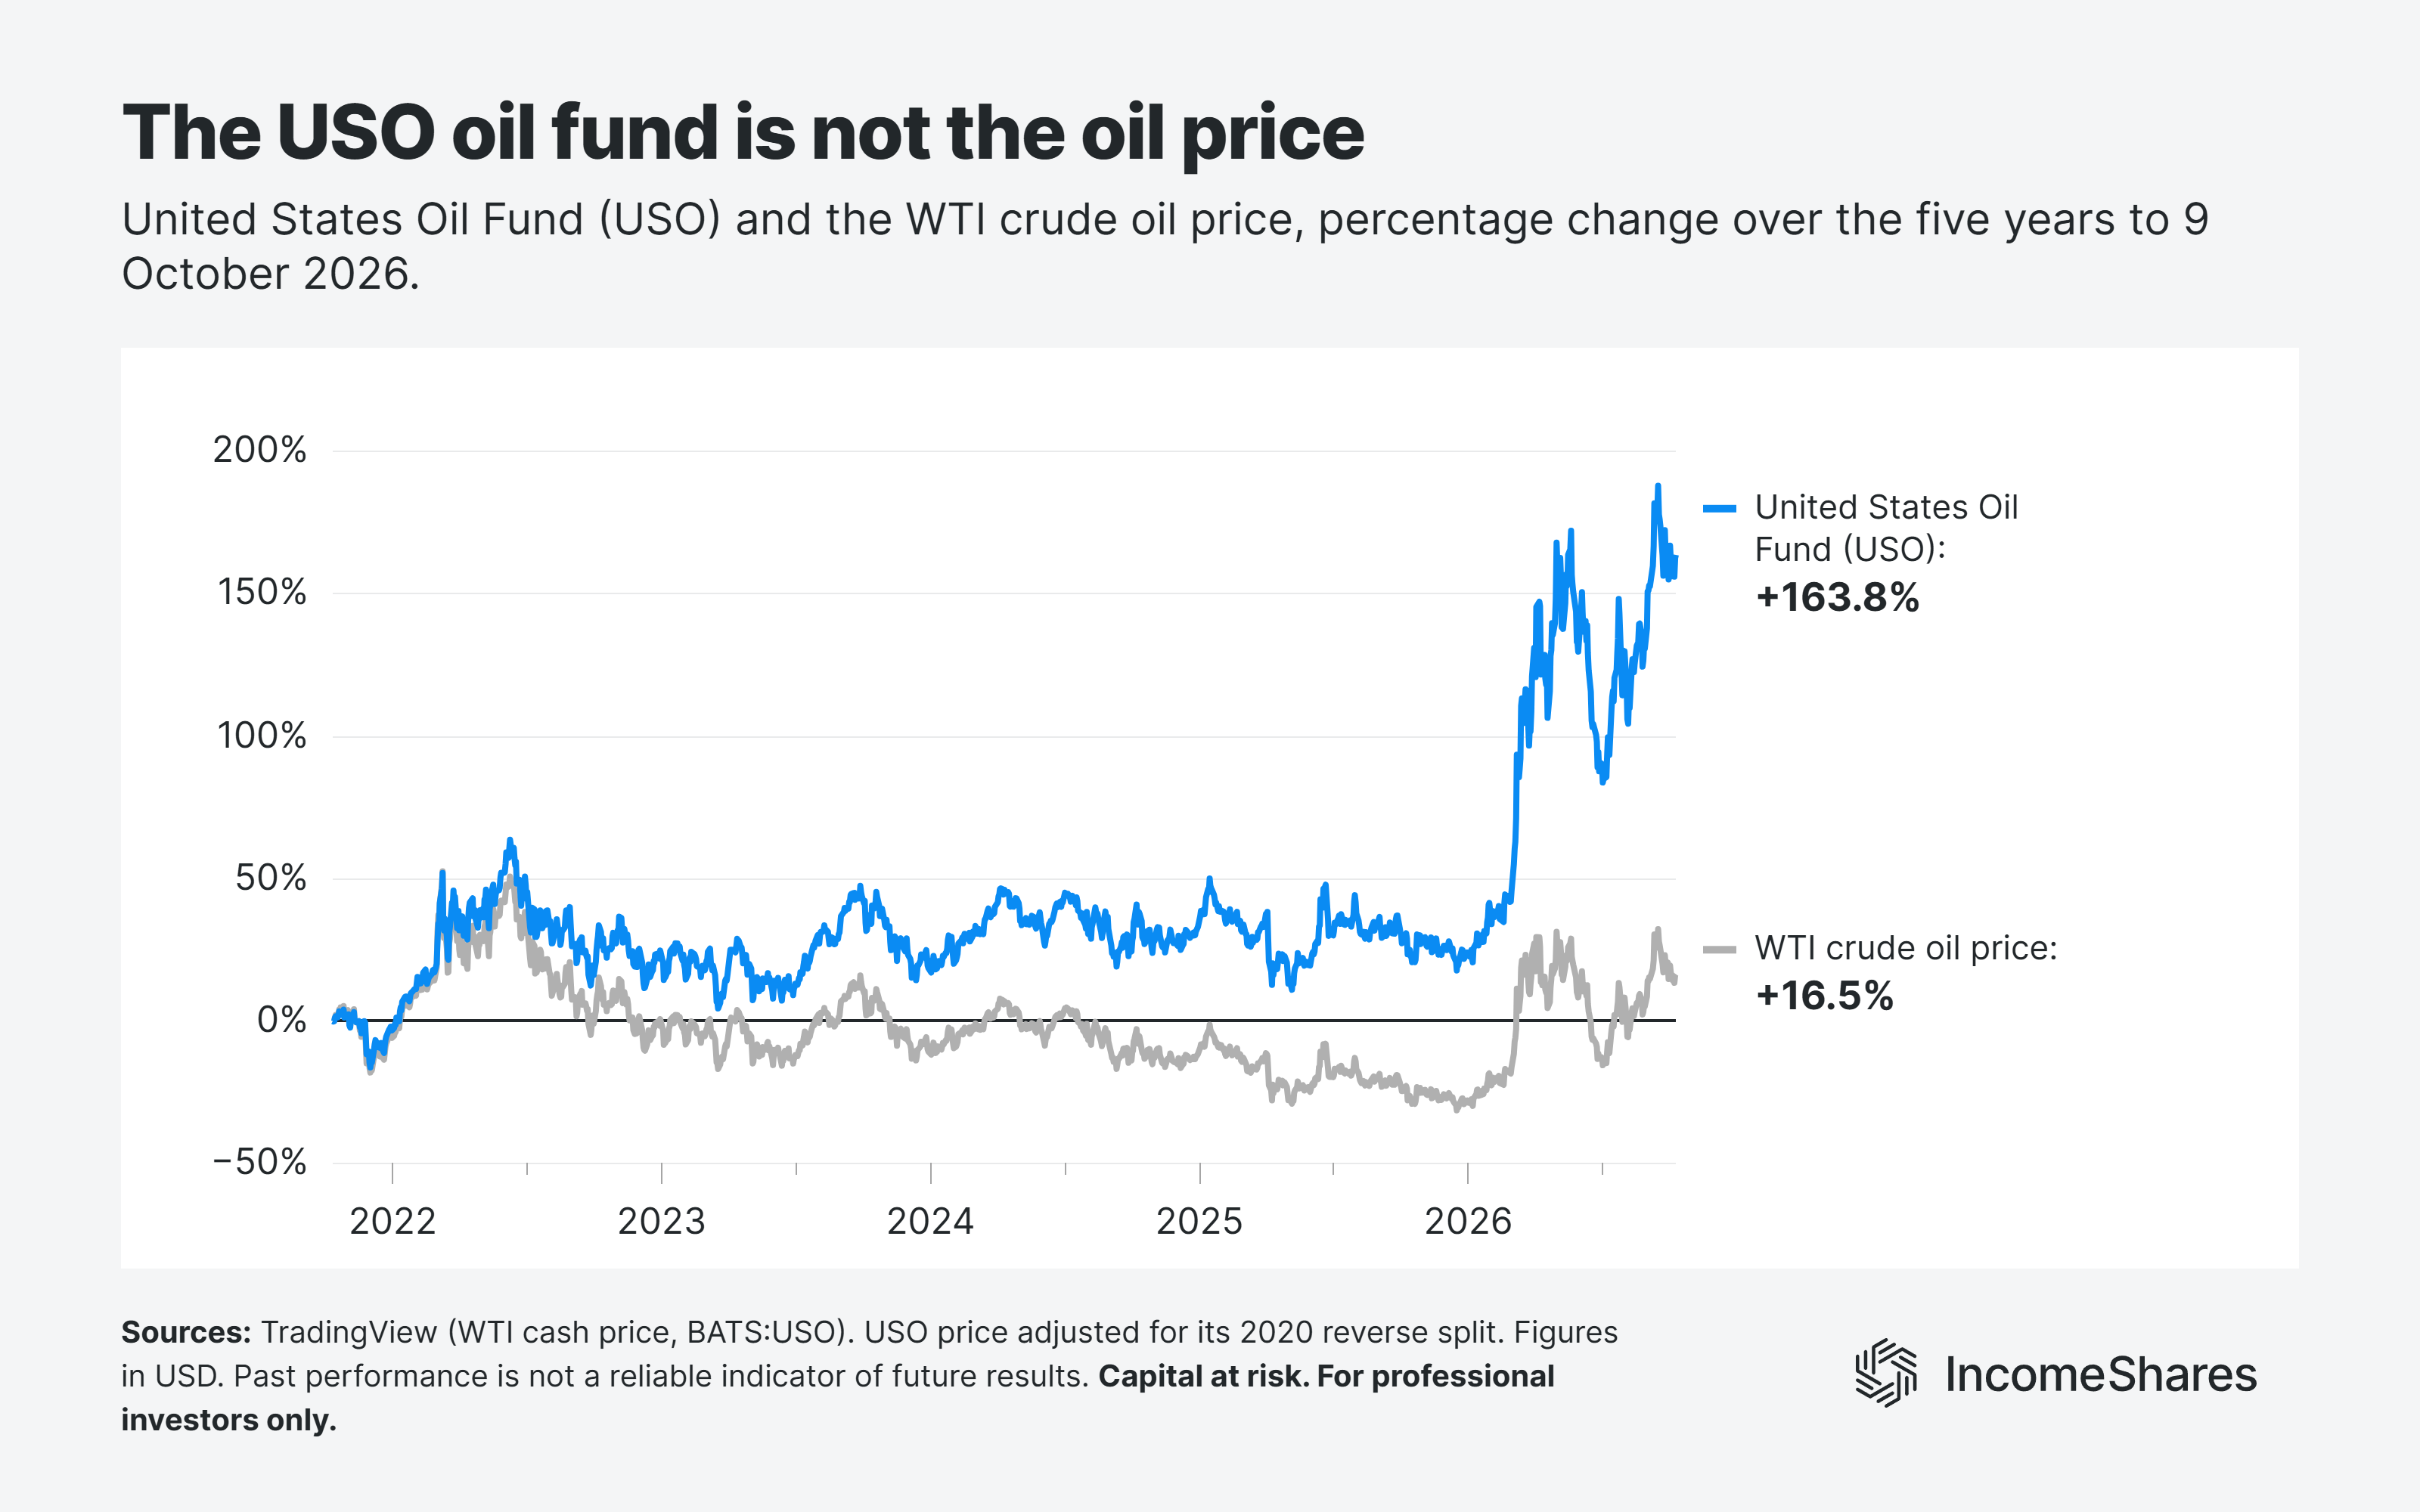
USO itself doesn’t move exactly like the oil price. That’s because it holds oil futures, which expire. And before each expiry, the fund “rolls” into the next month’s contract.
If the next month’s contract is cheaper (backwardation): the fund sells the current contract at a higher price and buys the next one at a lower price. So it can gain a bit extra on the oil price with that roll.
If the next month’s contract is more expensive (contango): the fund sells the current contract at a lower price and buys the next one at a higher price. So it can lose a bit against the oil price with that roll.
The chart below shows both over the last five years. Oil is up around 16%, while USO is up around 164%. Backwardation has helped the fund on most rolls since 2022. That’s also why USO rose 2.0% from 1 May to 30 September, while the oil price fell 6.2%.
How the WTI Oil+ Yield ETP performed in its first five months
Our ETP’s figures below come from Bloomberg, in US dollars. They run from its first net asset value (NAV) on 1 May to 30 September. They’re total returns, which assume the investor reinvested each income distribution back into the ETP.
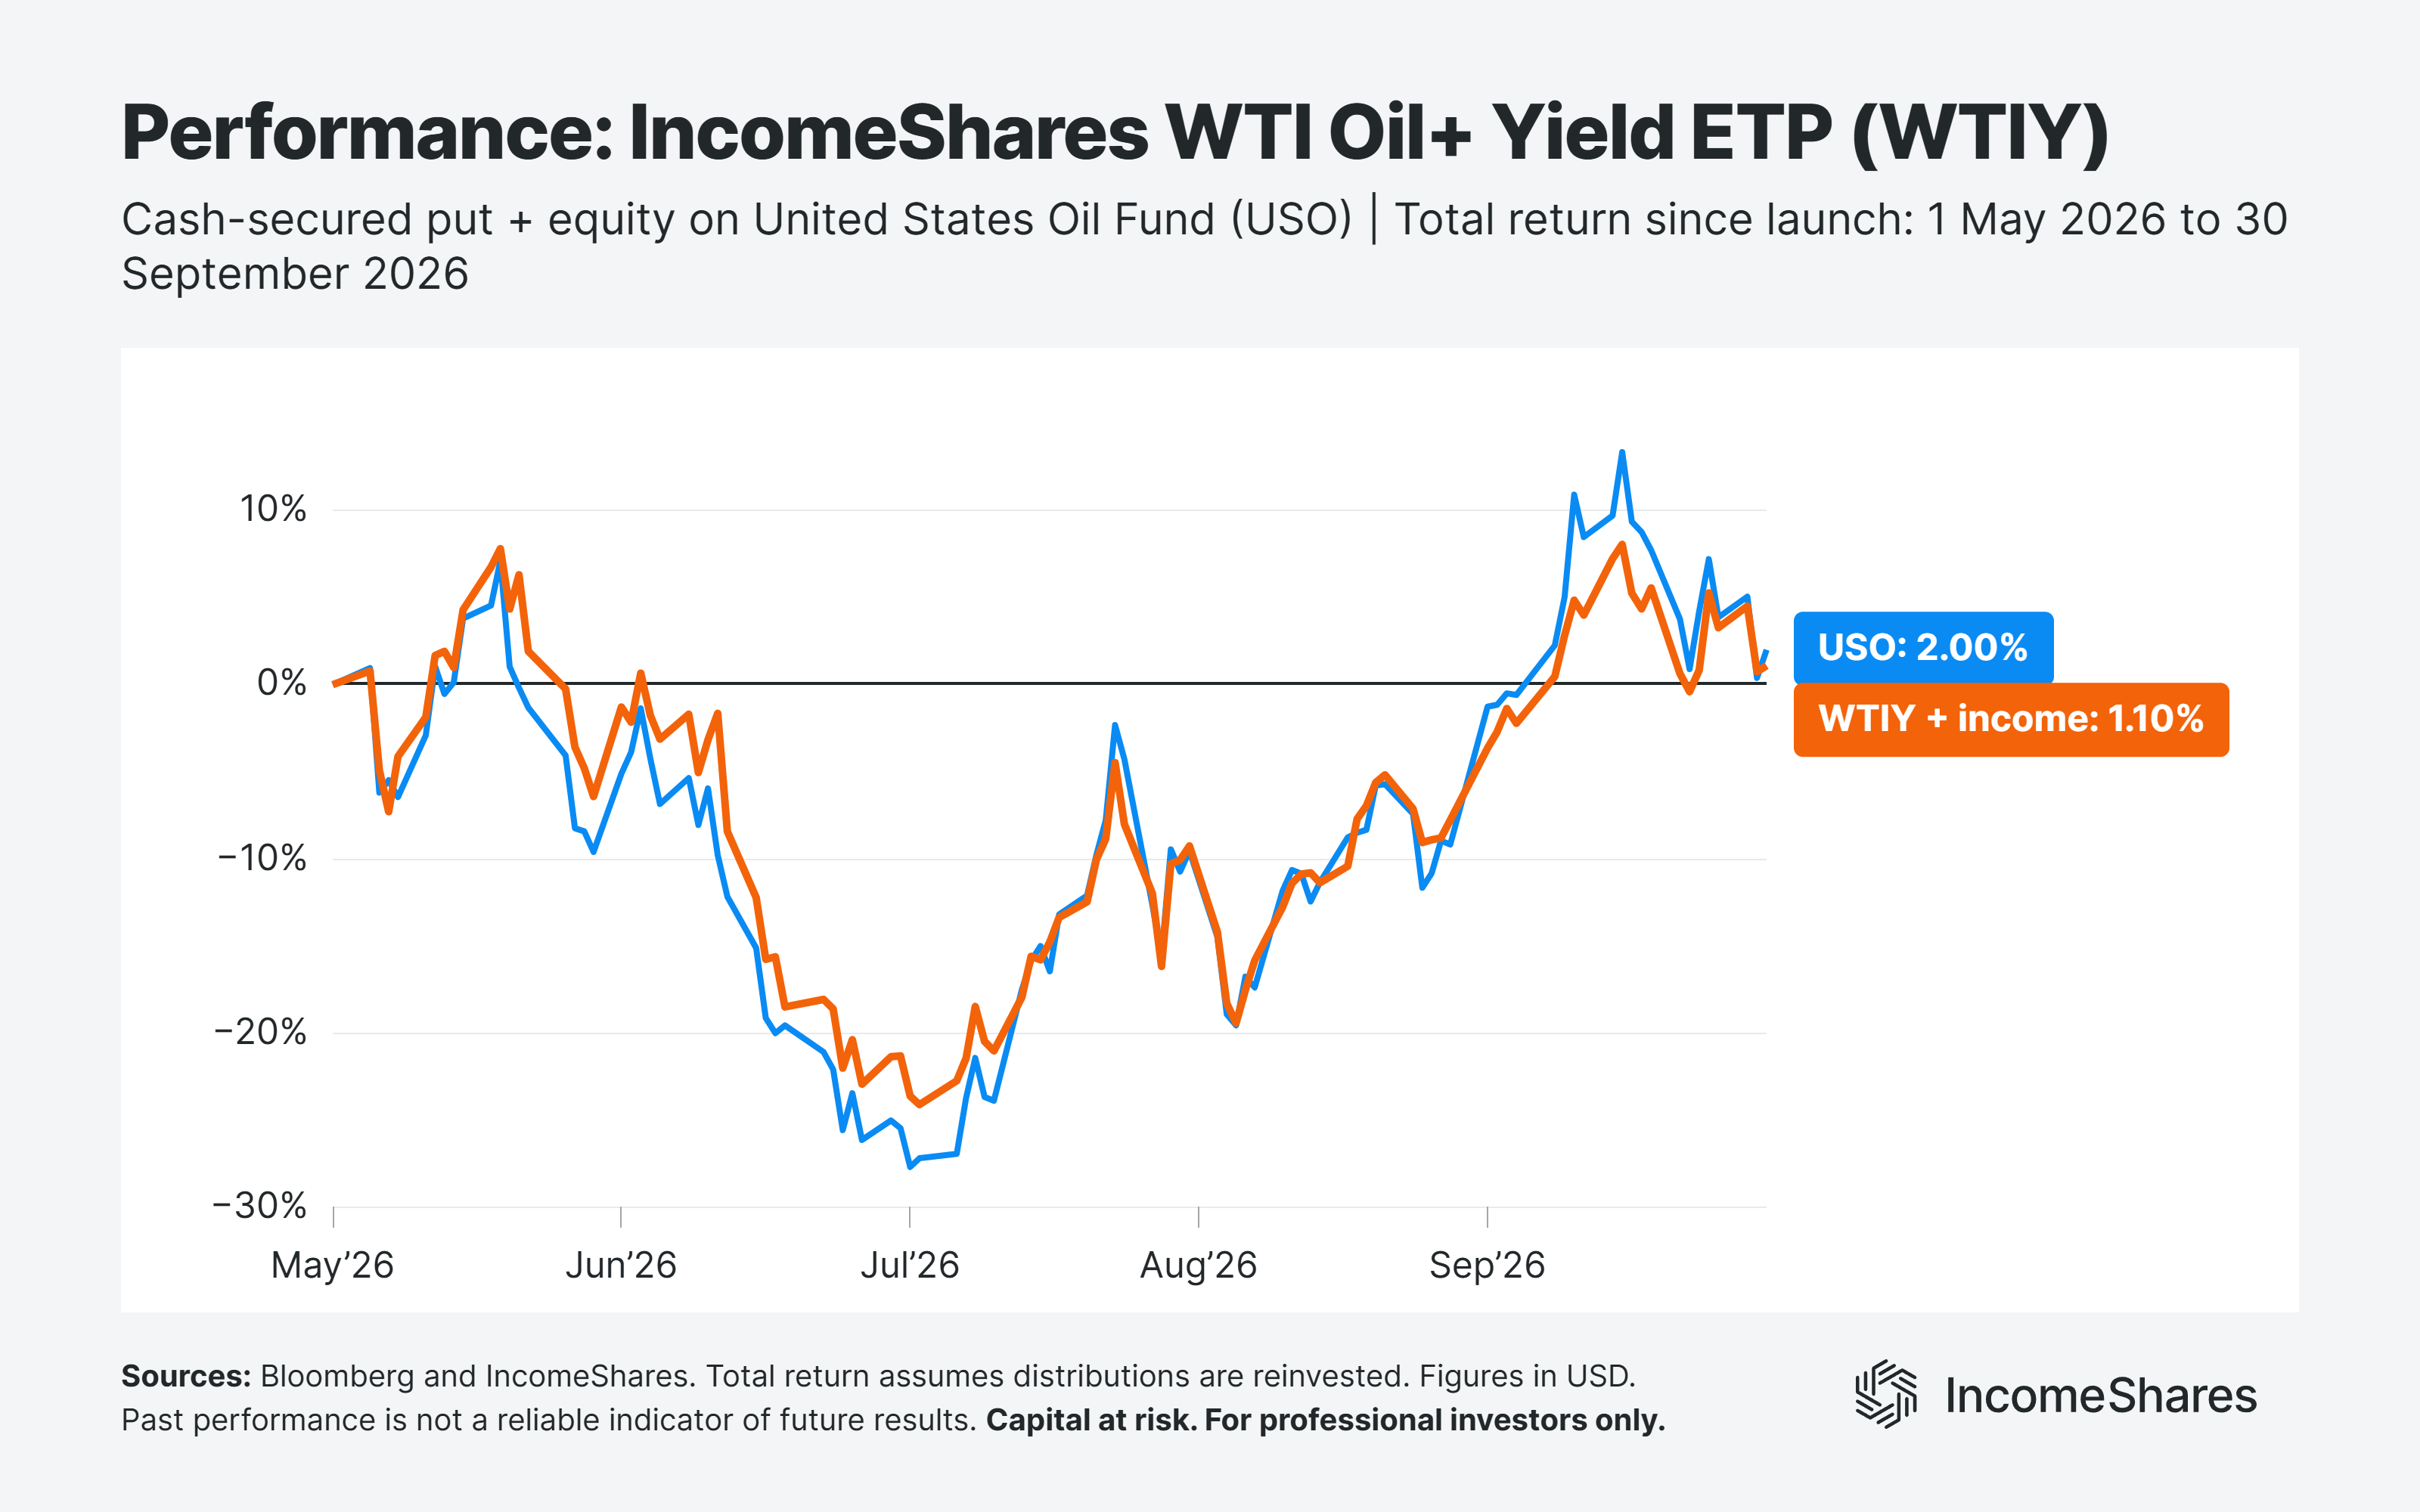
Oil fell, but the ETP still finished ahead of it. The chart below shows the oil price, USO, and our ETP since launch. Our ETP returned 1.1% with income reinvested, so it beat the oil price but finished behind USO.
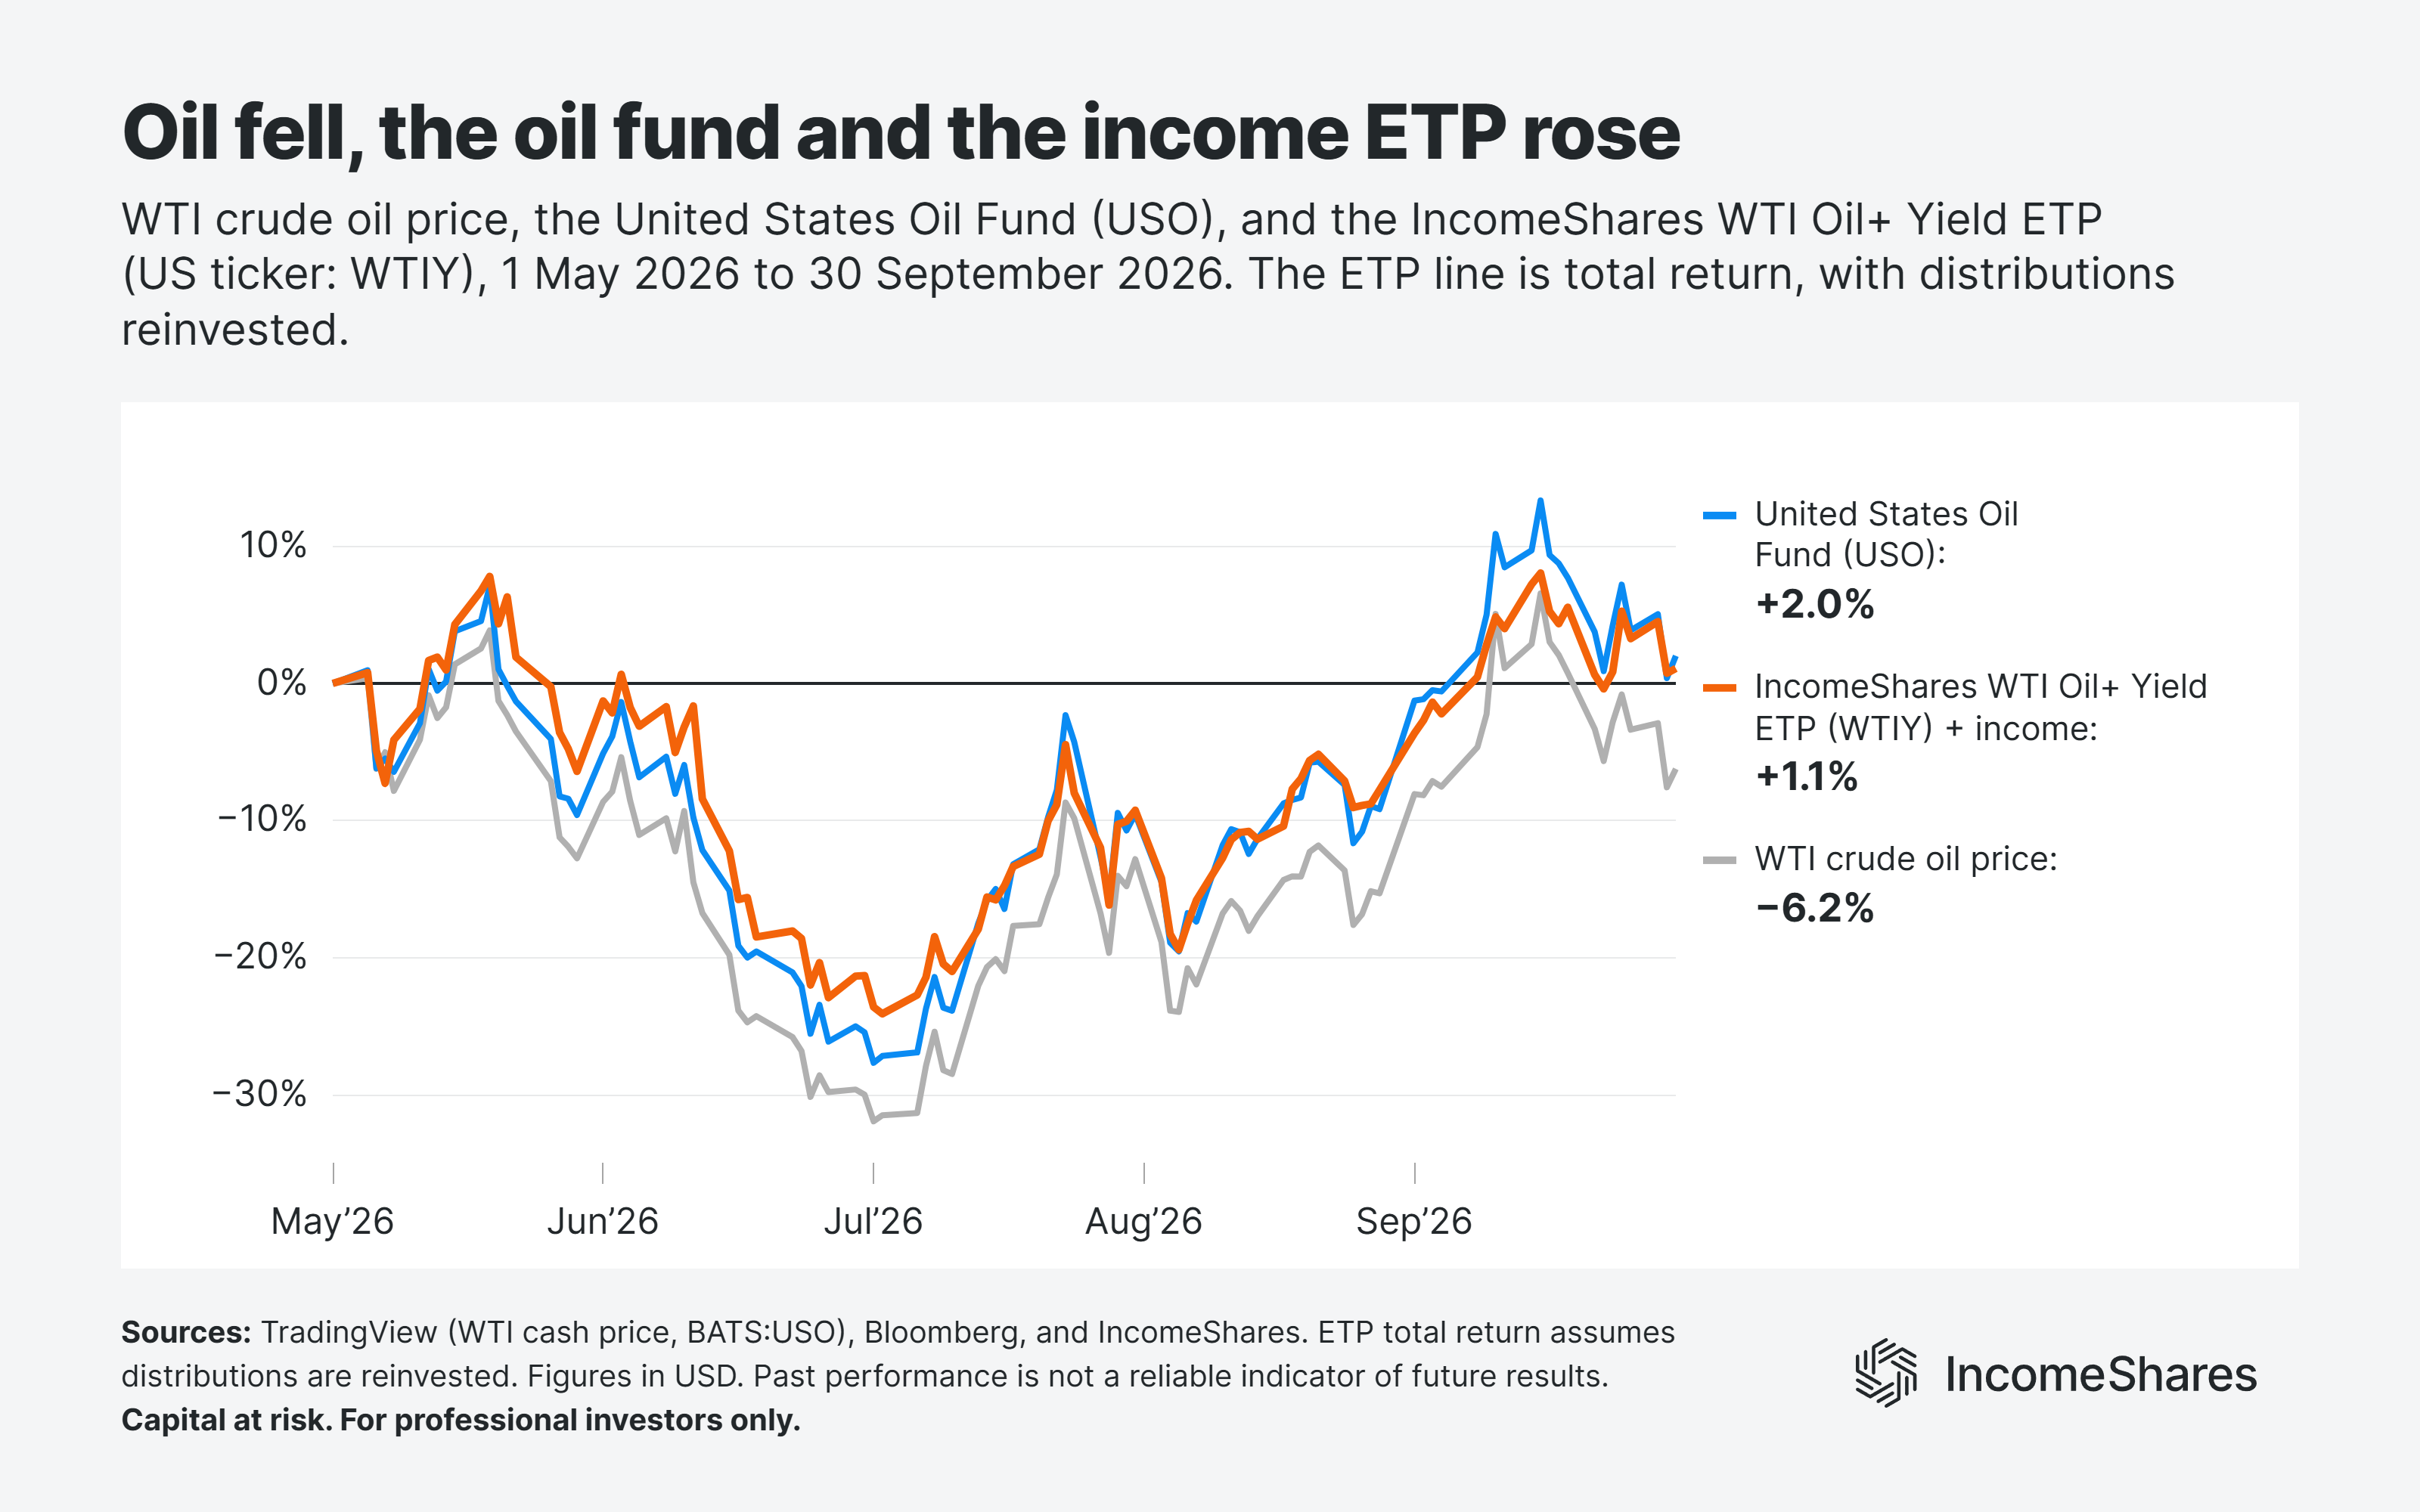
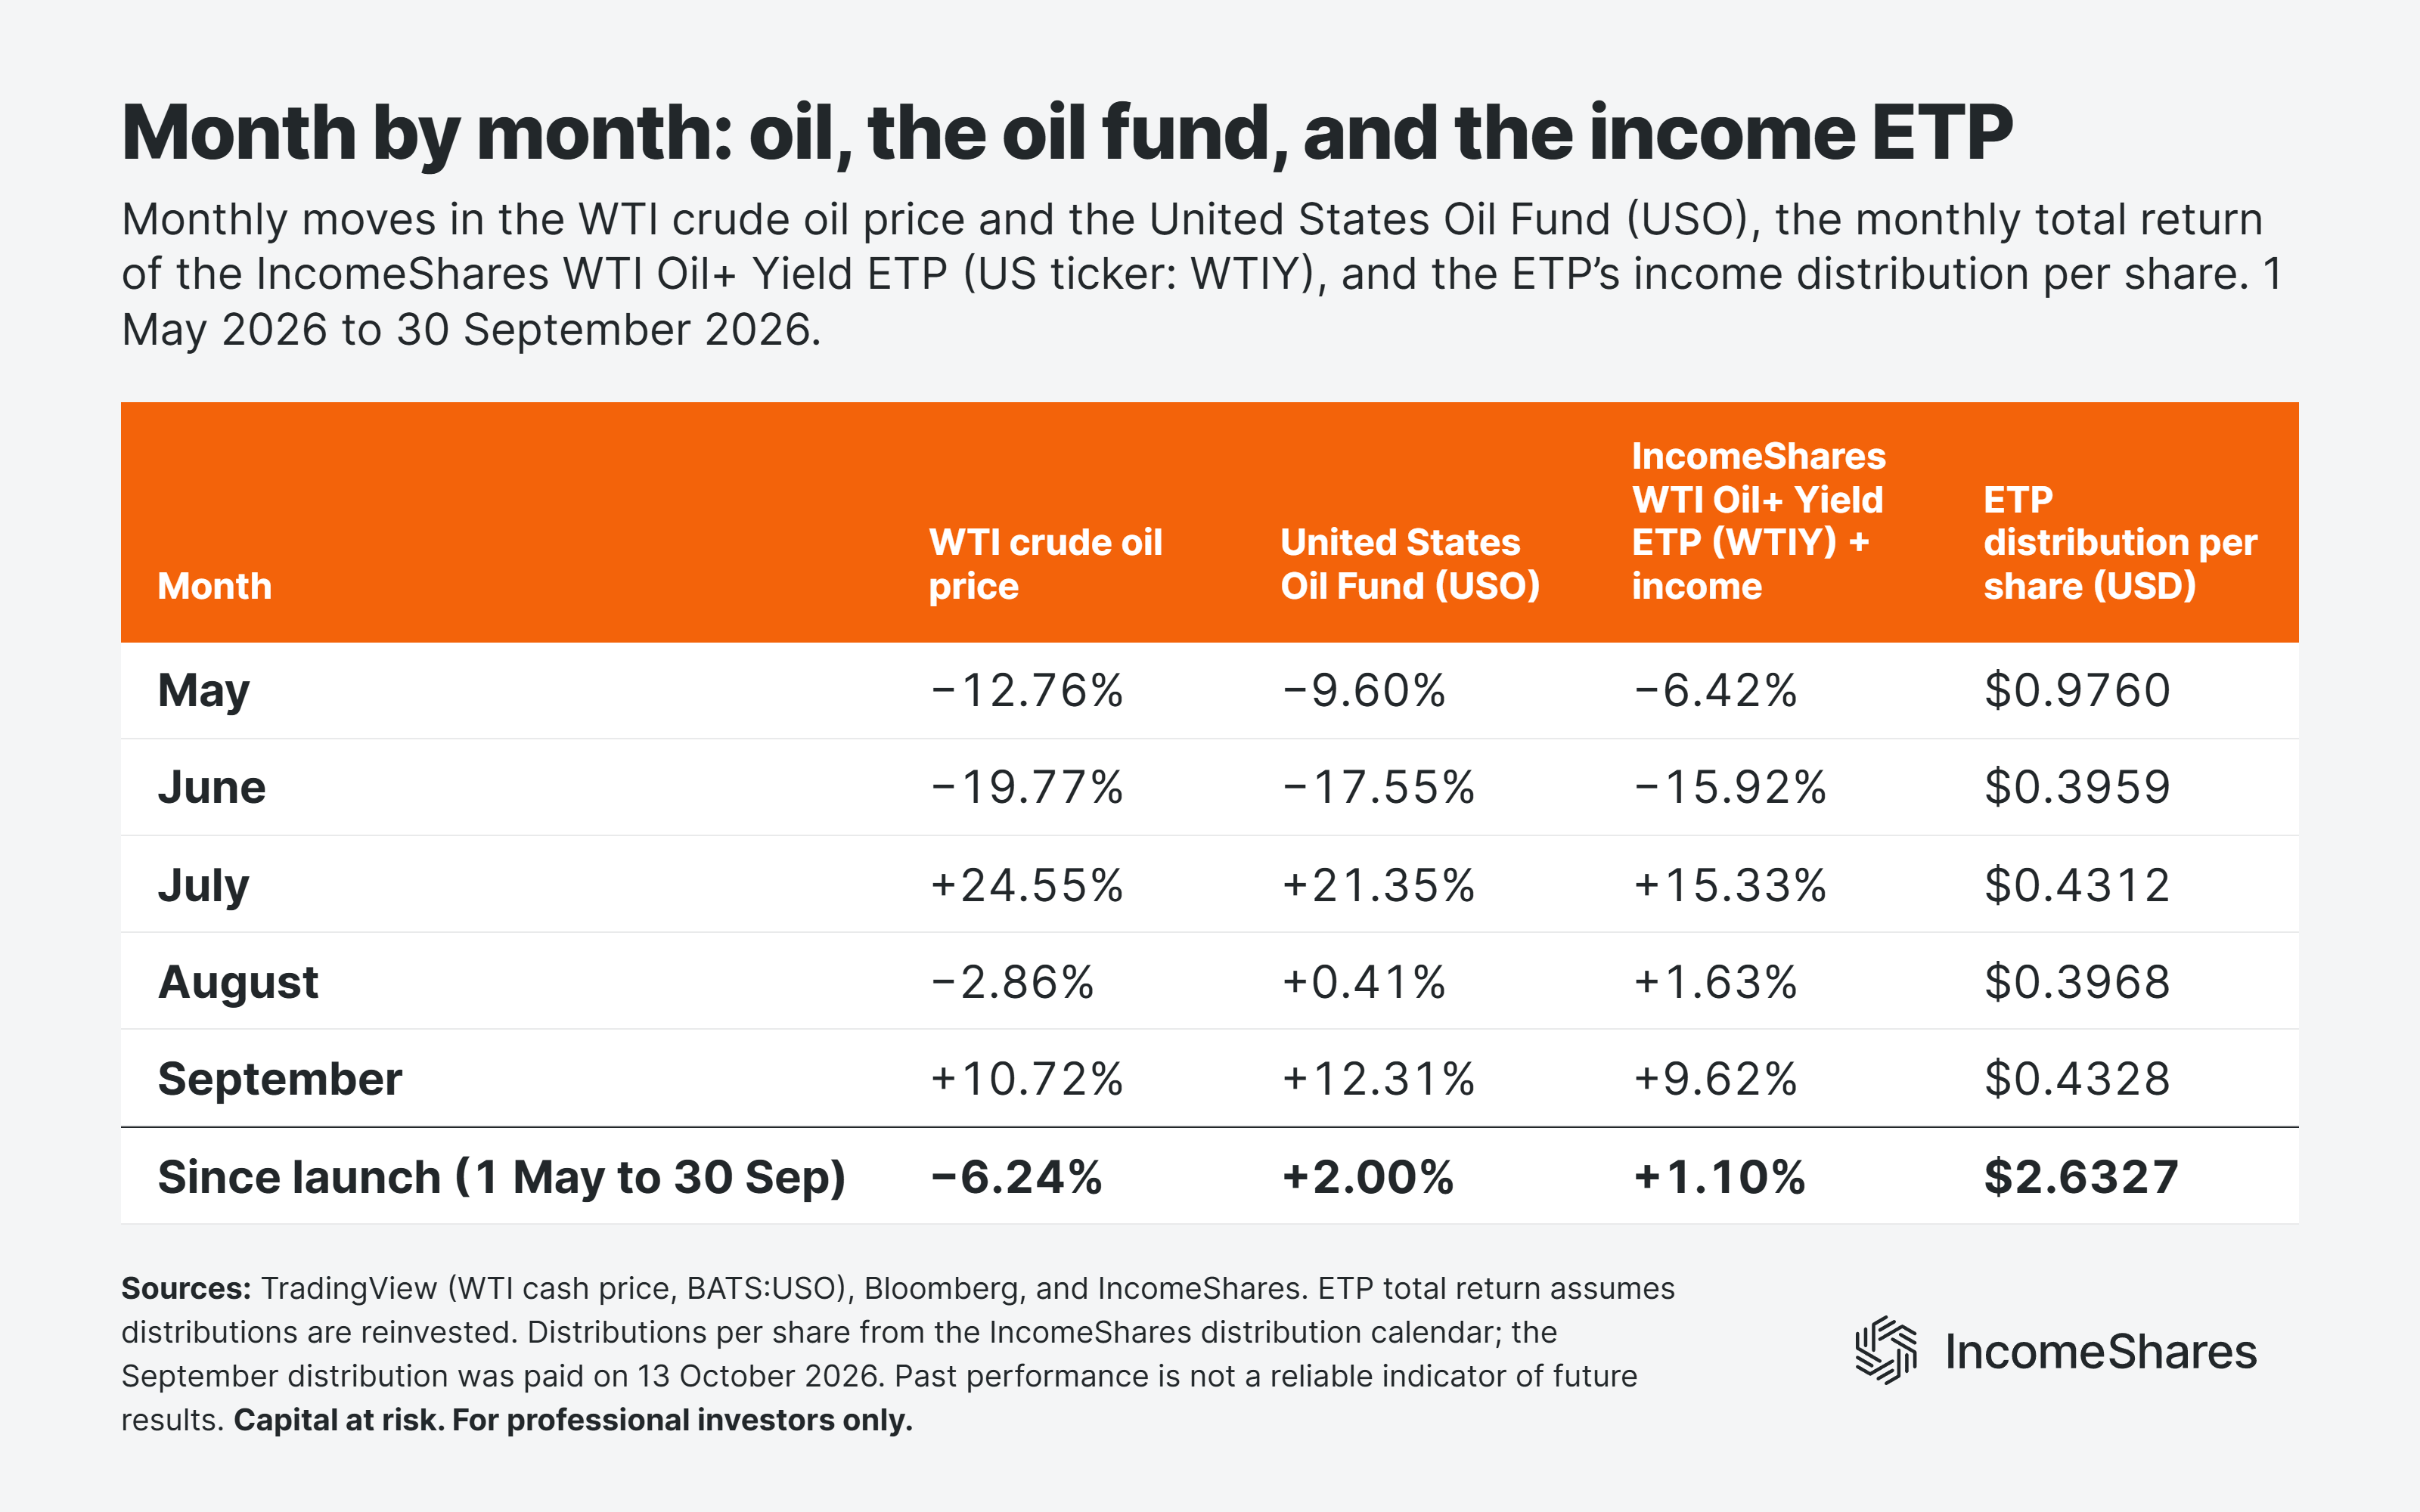
Most of the return came from the income. The ETP paid out five monthly income distributions totalling $2.63 a share, against a starting NAV of $10.19. Those payments came from the premiums we collected by selling put options. The table below shows each month’s distribution.
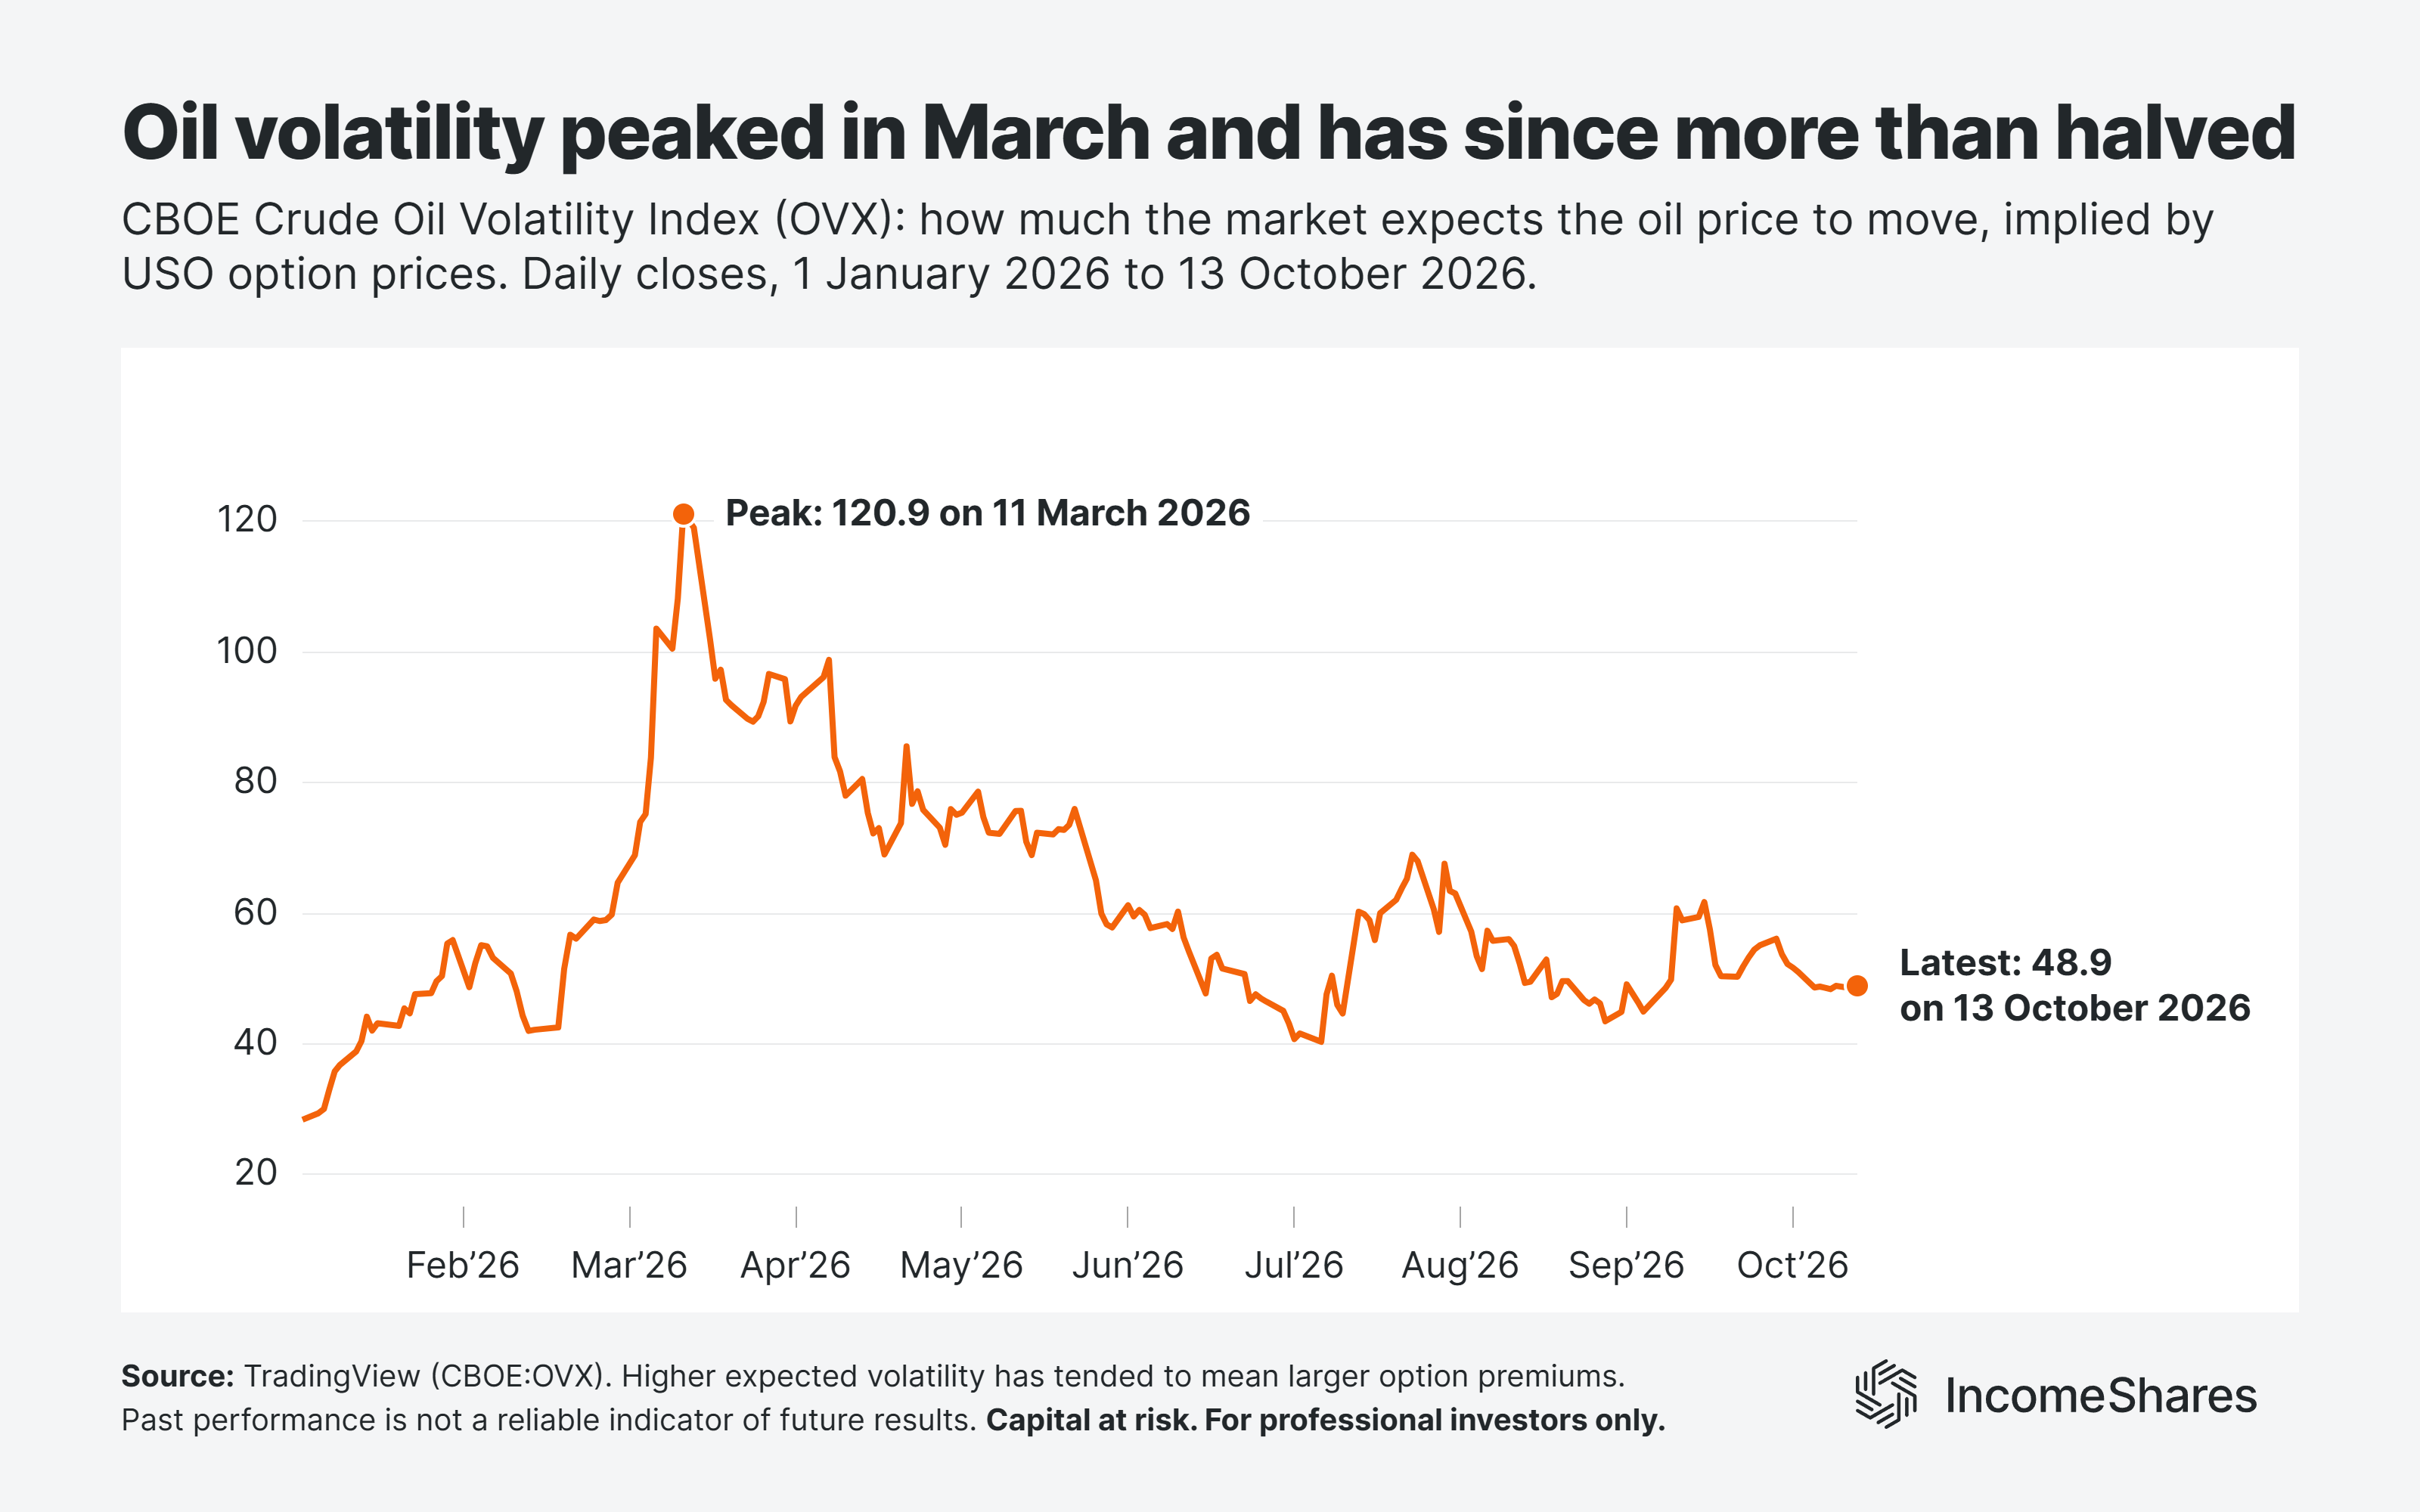
The premiums behind those distributions were large. The ETP’s annualised distribution yield was 121% in May, and between 63% and 68% since June (source: IncomeShares). That’s each monthly distribution as a share of the NAV, multiplied by twelve. Premium size depends partly on implied volatility, which is how much the market expects an asset to move. The oil volatility index (OVX) below measures that for oil, from USO option prices. It peaked at 121 in March and was still high in May. Since June, it has averaged around 50.
Oil whipsawed, and the strategy did what you’d expect. In May and June, USO fell 9.6% and 17.5% – and the ETP lost less in both (counting the income). In July and September, USO rose 21.4% and 12.3%, while the ETP rose less in both rallies. The premiums may help cushion part of a fall. But the ETP holds only part of its exposure in USO shares, so it can capture less of a rise.
A few caveats to keep in mind
Oil can fall fast. WTI fell around 16% in late May, when the US and Iran started ceasefire talks. Our ETP fell with it. Premiums may cushion part of a fall like that, but the ETP still holds USO.
The roll can go the other way. In 2020, deep contango cost USO around forty percentage points against the oil price. If the curve moves back into contango, each roll could cost the fund money (and our ETP holds that fund).
The income isn’t fixed. The distributions depend on the premiums we collect, so they may vary. And the ETP’s holdings trade in dollars, so exchange rates affect what UK and European investors receive.
Key highlights
Oil pays nothing on its own. Earning income from oil means holding something built on it, like producer shares or an ETP that sells options.
An oil fund isn’t the oil price. It rolls futures each month, and the roll can add to the return or take from it.
Selling puts means our ETP holds only part of its exposure in USO shares, so it can capture less of a rally. The premiums it collects may help cushion part of a fall. With income reinvested, it returned 1.1% since launch – ahead of the oil price, but behind USO.
Votre capital est exposé à un risque si vous investissez. Vous pouvez perdre la totalité de votre investissement. Veuillez consulter l’avertissement complet sur les risques ici
Produits associé:

Stratégie
Covered call
Rendement des
distributions
12.10%

Stratégie
Covered Call
Rendement des
distributions
12.52%

Stratégie
Put garanti par des liquidités + Actions
Rendement des
distributions
66.84%

Stratégie
Put garanti par des liquidités + Actions
Rendement des
distributions
56.56%

Stratégie
Put garanti par des liquidités + Actions
Rendement des
distributions
21.46%

Stratégie
Put garanti par des liquidités + Actions
Rendement des
distributions
59.03%

Stratégie
Put garanti par des liquidités + Actions
Rendement des
distributions
58.59%