Author
Jonathan Hobbs, CFA
Date
23 Sep 2026
Category
Education
In the Money vs Out of the Money Options Explained
Your capital is at risk if you invest. You could lose all your investment. Please see the full risk warning here.
IncomeShares exchange-traded products (ETPs) hold an underlying asset (like a stock or gold) and sell options on it. Every option has a strike price - the price at which the option buyer can potentially buy or sell the underlying asset. Where that strike price lies against the market price makes the option "in the money" or "out of the money" for the option buyer.
As for option sellers, should they sell in the money or out of the money options for income? This article weighs up the potential risks and rewards for each – for selling both call and put options.
Selling in the money call options
A call option gives the buyer the right to buy an underlying asset at the strike price, on or before expiry. Using that right is called exercising the option. If the buyer exercises, the seller must sell the asset at that strike price.
A call option is in the money when the market price is above the strike price. That's because exercising it would pay off for the call buyer.
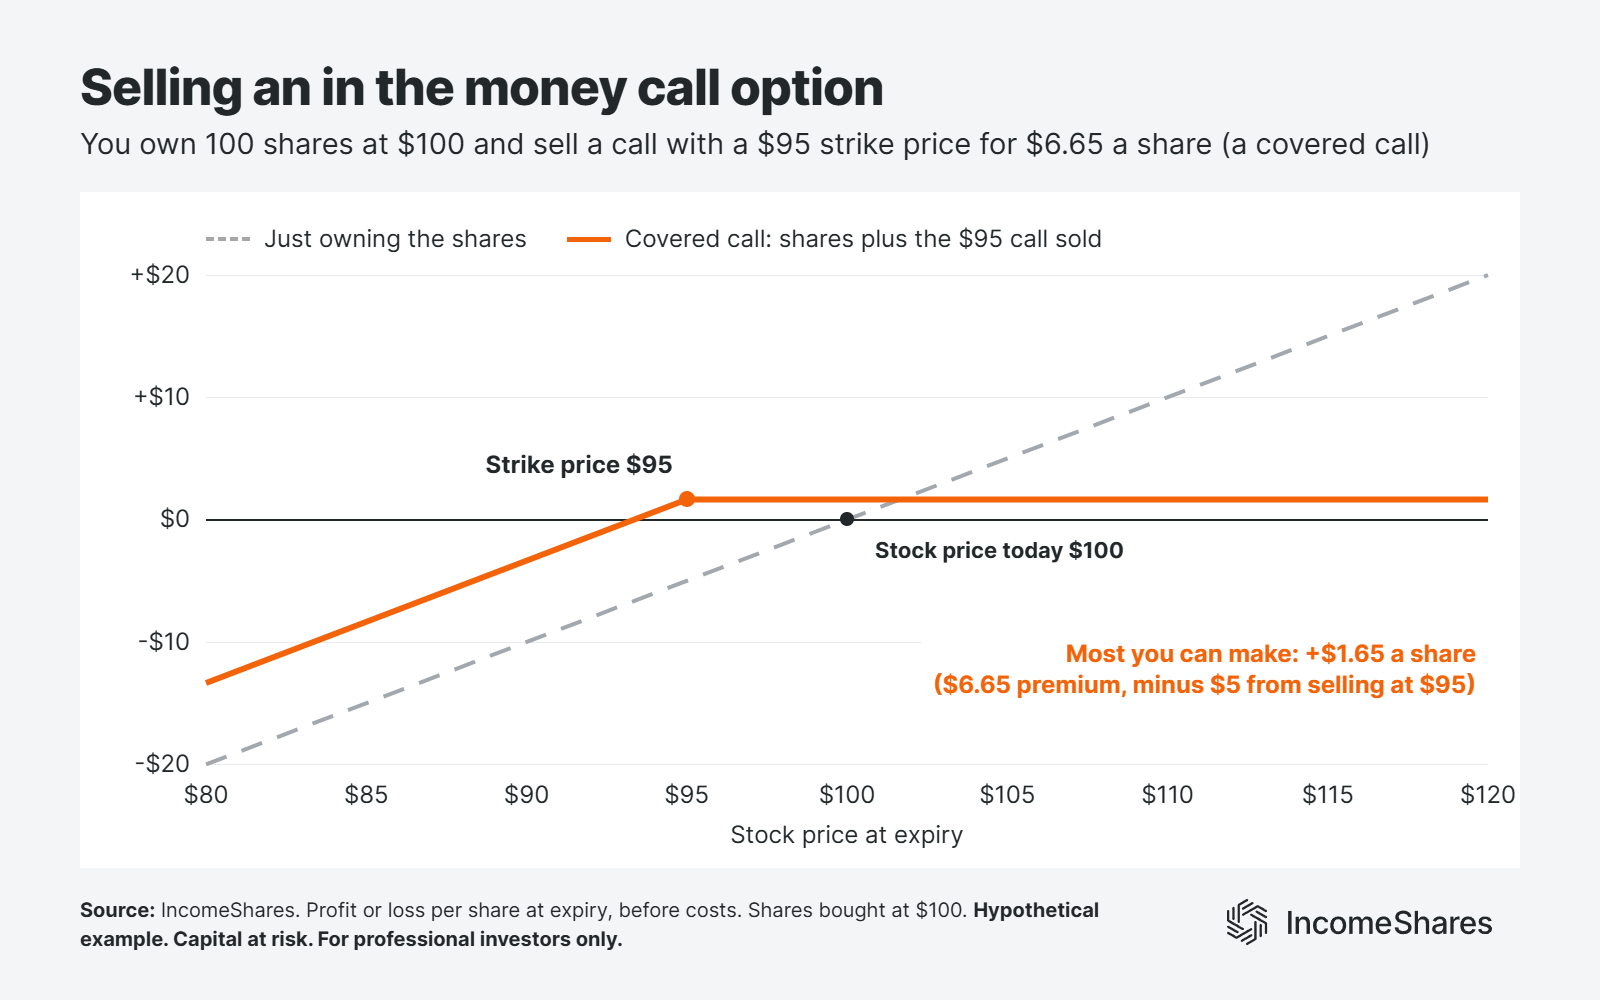
Say you own 100 shares of a $100 stock. You then sell a call option on those shares with a $95 strike price (a covered call). Now, the call option would already be $5 in the money – since the buyer "could" buy the shares for $95 and sell them for $100 today.
The buyer pays you a fee up front, called the premium – which you keep whether the buyer exercises or not. For an in the money call the buyer pays more, say $6.65 a share. That's the $5 it's worth today, plus $1.65 for the chance the stock rises further before expiry. Traders call the $5 the option's intrinsic value, and the $1.65 its extrinsic value.
The buyer won't normally exercise straight away. Using the option today would get them $5 – but they've just paid you $6.65 for it. They'd rather wait and see if the stock goes higher. So you (the option seller) keep the shares for now, and you keep the $6.65 (whatever happens next).
If the stock is still above $95 at expiry, you sell your shares for the $95 strike price. You've now given up every gain above $95, but you still earned that $6.65 premium up front. What you get in return is a potential cushion.
If the stock falls to $90 instead, your shares lose $10 but you've collected $6.65. The call expires worthless to the option buyer – meaning you still keep the shares.
The diagram below shows your profit or loss per share at expiry, against just owning the shares.
Selling out of the money call options
A call is out of the money when the market price is below the strike price. Exercising it wouldn't pay off for the option buyer.
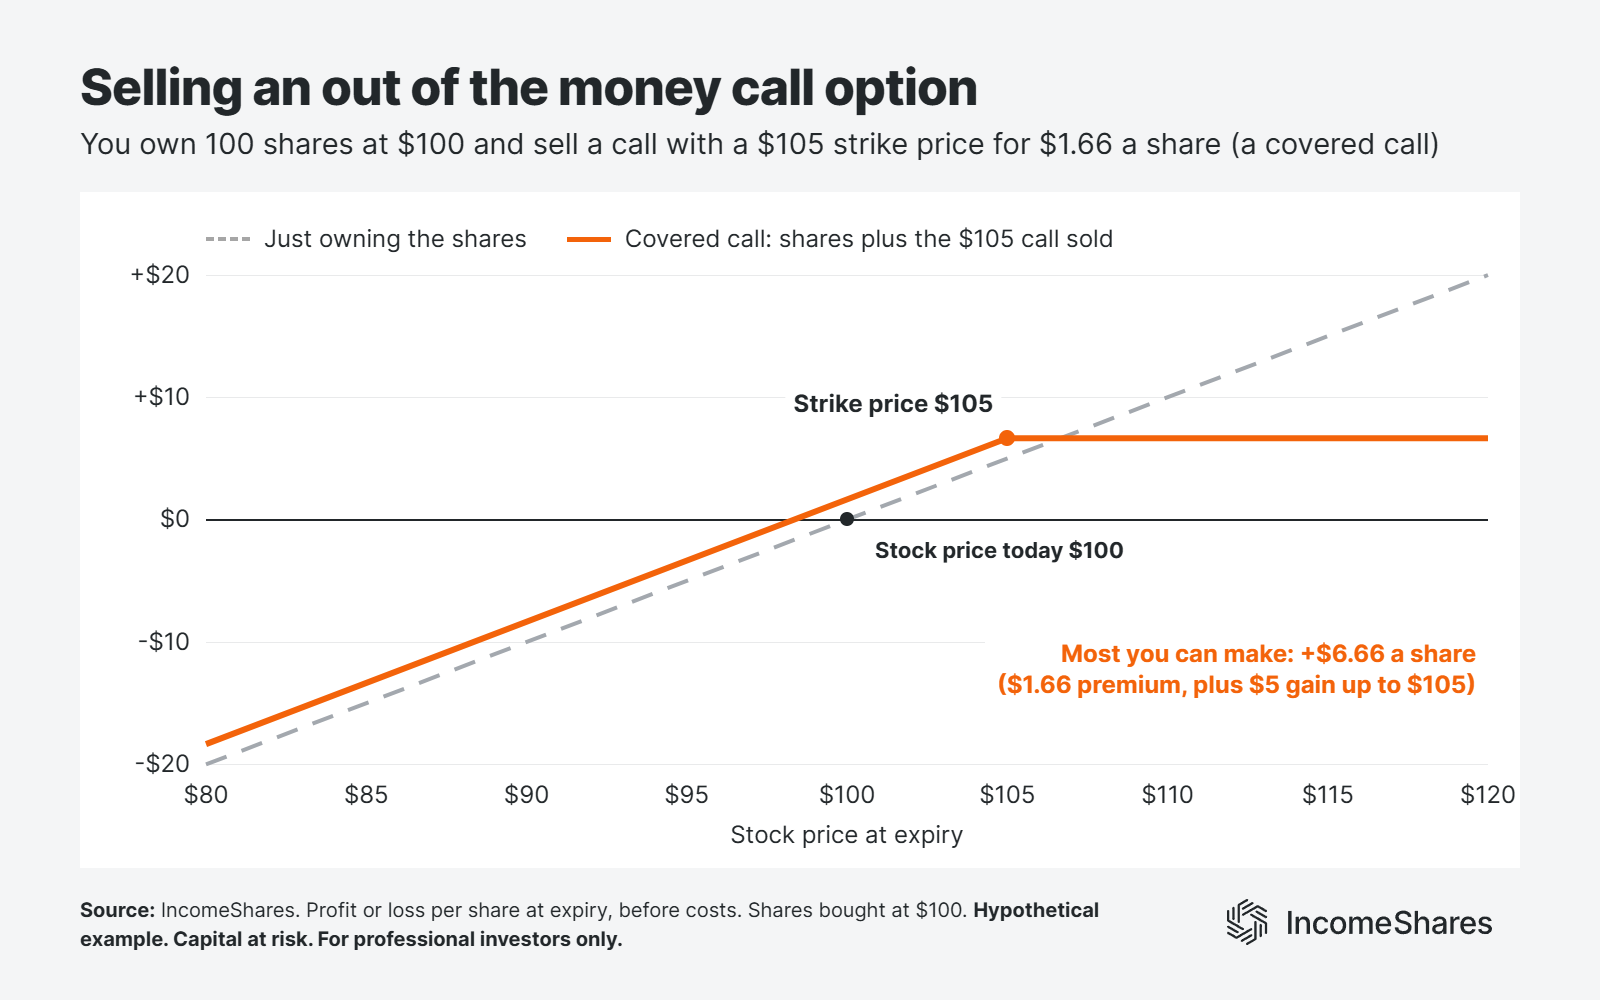
Now suppose you sell a call option with a $105 strike price on the same shares. It's $5 out of the money, so it's worth nothing to the buyer if exercised today. The buyer pays you only for the "chance" the stock rises above $105 before expiry. Since there's less chance of that happening, they pay less money for the call – say $1.66 a share. That's all extrinsic value, since there's no intrinsic value to pay for. It's also a quarter of what the $95 call paid.
If the stock stays below $105, the option expires worthless to the buyer – so they won't exercise. That means you keep the shares, any gain up to $105, and the $1.66.
If the stock rises past $105, you sell the shares for $105 and give up the gains above it.
If the stock falls to $90, your cushion is only $1.66.
So the out of the money call has paid you less up front than the in the money call here. But it also let you hold onto your shares for a bigger potential gain. The diagram below shows the difference: the flat line is higher, but the cushion on the left is thinner.
Selling in the money put options
A put option works the other way round. It gives the buyer the right to sell an asset at the strike price, on or before expiry. If the buyer exercises, the seller must buy the asset at the strike price.
A put option is in the money when the market price is below the strike price. That's because exercising it would pay off for the put buyer.
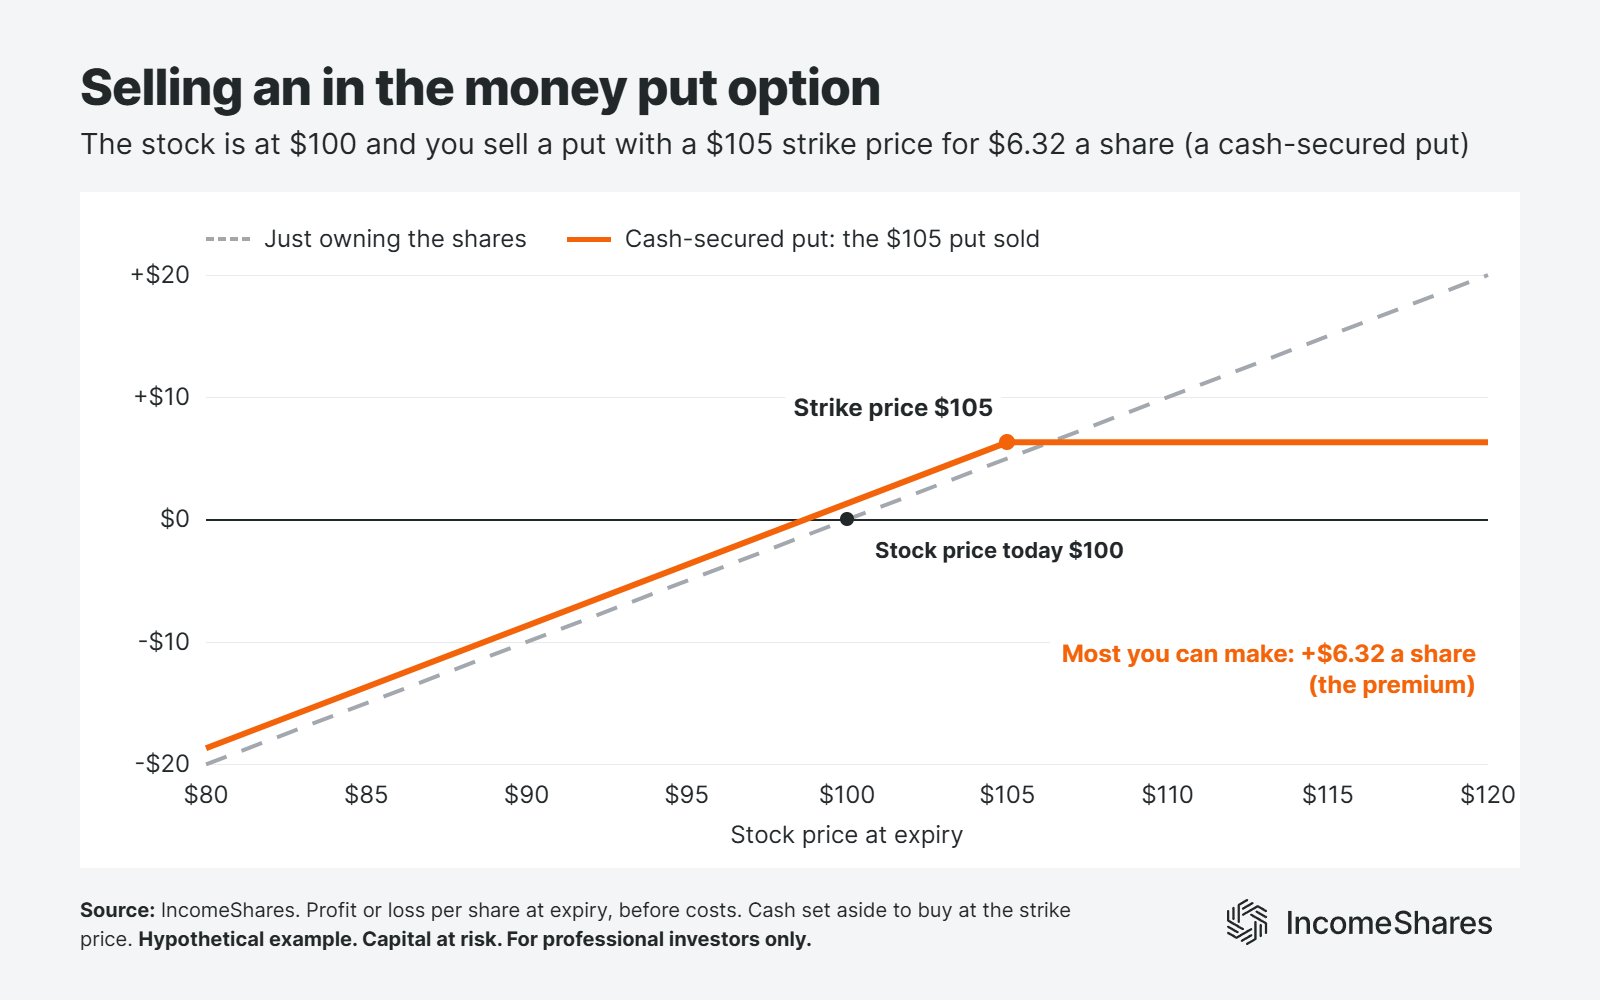
Now suppose you sell a put option on that same $100 stock with a $105 strike price. You also set aside enough cash to buy the shares at $105 if you need to (a cash-secured put). The put is already $5 in the money. The buyer "could" buy the shares for $100 and sell them to you for $105 today.
Again, the buyer pays more for an in the money put option – say $6.32 a share. That's the $5 it's worth today (the intrinsic value), plus $1.32 of extrinsic value for the chance the stock falls further before expiry. And again, the buyer won't normally exercise straight away, since that would throw away the $1.32 they've just paid. You keep the $6.32 whatever happens next.
If the stock stays below $105, you buy the shares for the $105 strike price. That's more than they're worth in the market, but the $6.32 premium may help offset the difference.
If the stock falls to $90, you buy at $105, so you're $15 behind on the shares, but you've collected $6.32.
If the stock rises above $105, the put expires worthless to the buyer. You keep the $6.32 without buying any shares.
The deeper a put is in the money, the more it can behave like owning the stock. The diagram below shows that: the orange line runs close to the dashed one, lifted by $1.32 of extrinsic value.
Selling out of the money put options
A put is out of the money when the market price is above the strike price. Exercising it wouldn't pay off for the put buyer.
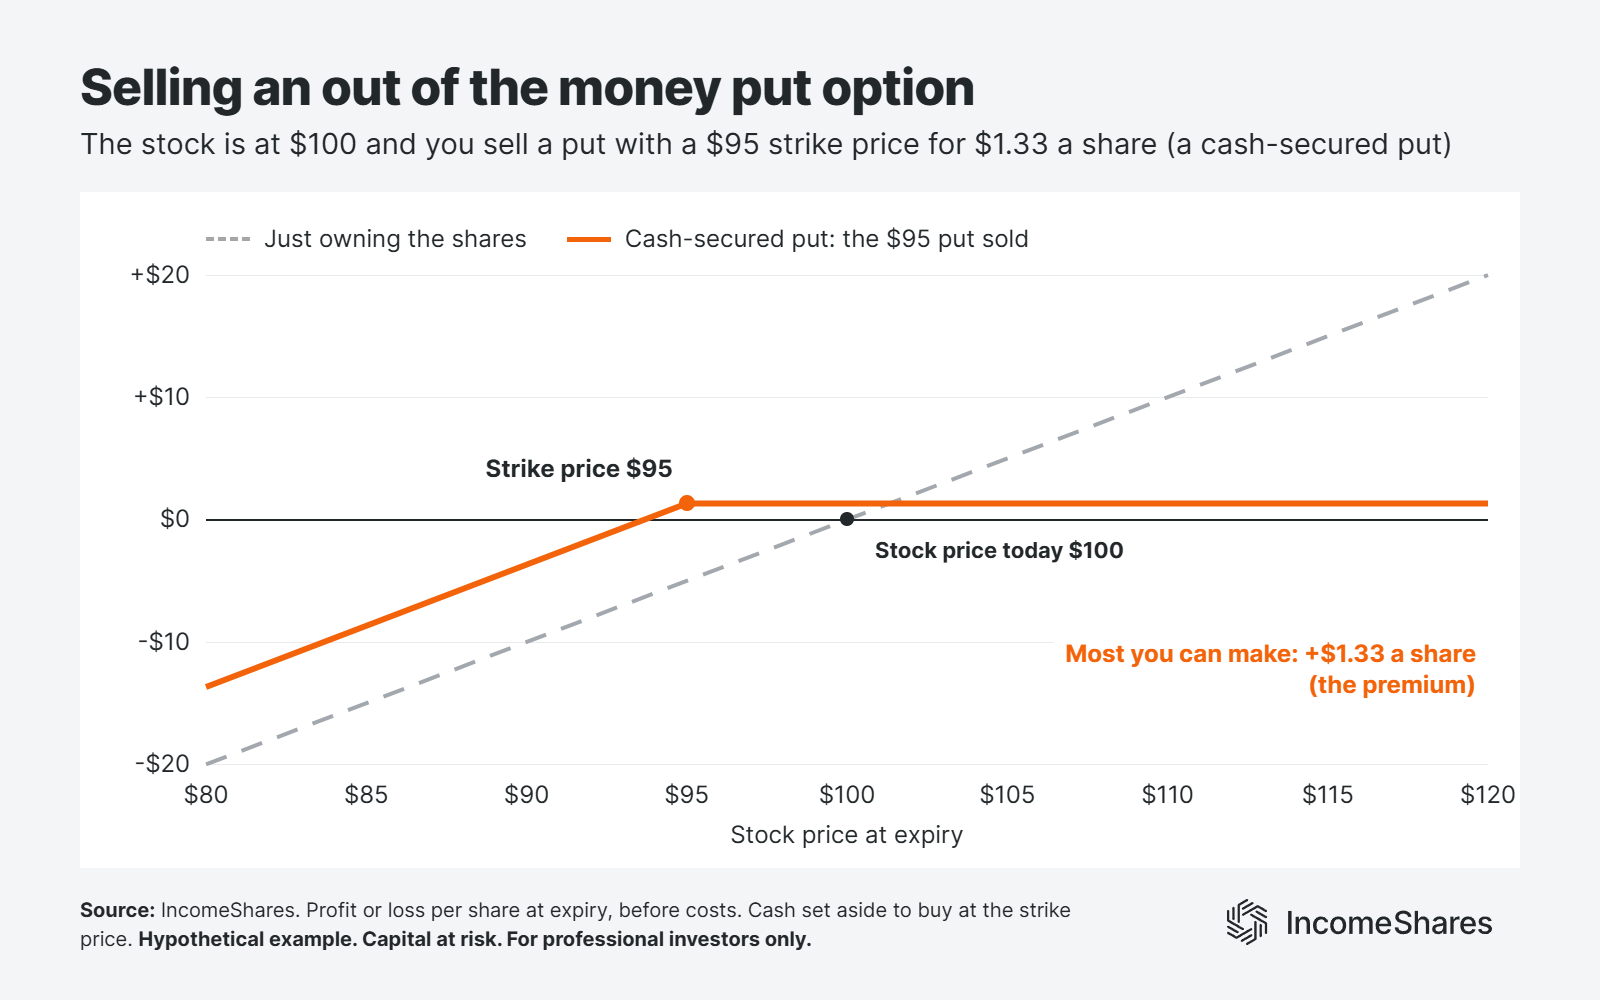
Now suppose you sell a put option with a $95 strike price on the same stock instead. It's $5 out of the money, so it's worth nothing to the buyer if exercised today. The buyer pays you only for the "chance" the stock falls below $95 before expiry. Since there's less chance of that happening, they pay less – say $1.33 a share. That's all extrinsic value, since there's no intrinsic value to pay for. It's also about a fifth of what the $105 put paid.
If the stock stays above $95, the option expires worthless to the buyer – so they won't exercise. You keep the $1.33 and never buy the shares.
If the stock falls through $95, you buy the shares for $95, more than they're then worth. The $1.33 may help offset the difference.
If the stock falls to $90, you buy at $95, so you're $5 behind on the shares, but you've collected $1.33.
So the out of the money put has paid you less up front than the in the money put. But you buy the shares less often, and at a lower price when you do. The diagram below shows the flat line sitting lower, and the slope starting further to the left.
In the money vs out of the money for option sellers
Nobody knows in advance which choice will be more profitable overall, since that depends on where the price goes.
Sell in the money and you collect more up front, but the buyer is more likely to exercise.
Sell out of the money and you collect less, but you're more likely to keep your shares (calls) or your cash (puts).
Traders use delta as a rough guide to that chance of exercise. In this example, the in the money options had a delta of around 0.7, and the out of the money ones around 0.3. So roughly a 70% chance of exercise against 30%. Keep in mind that delta changes all the time.
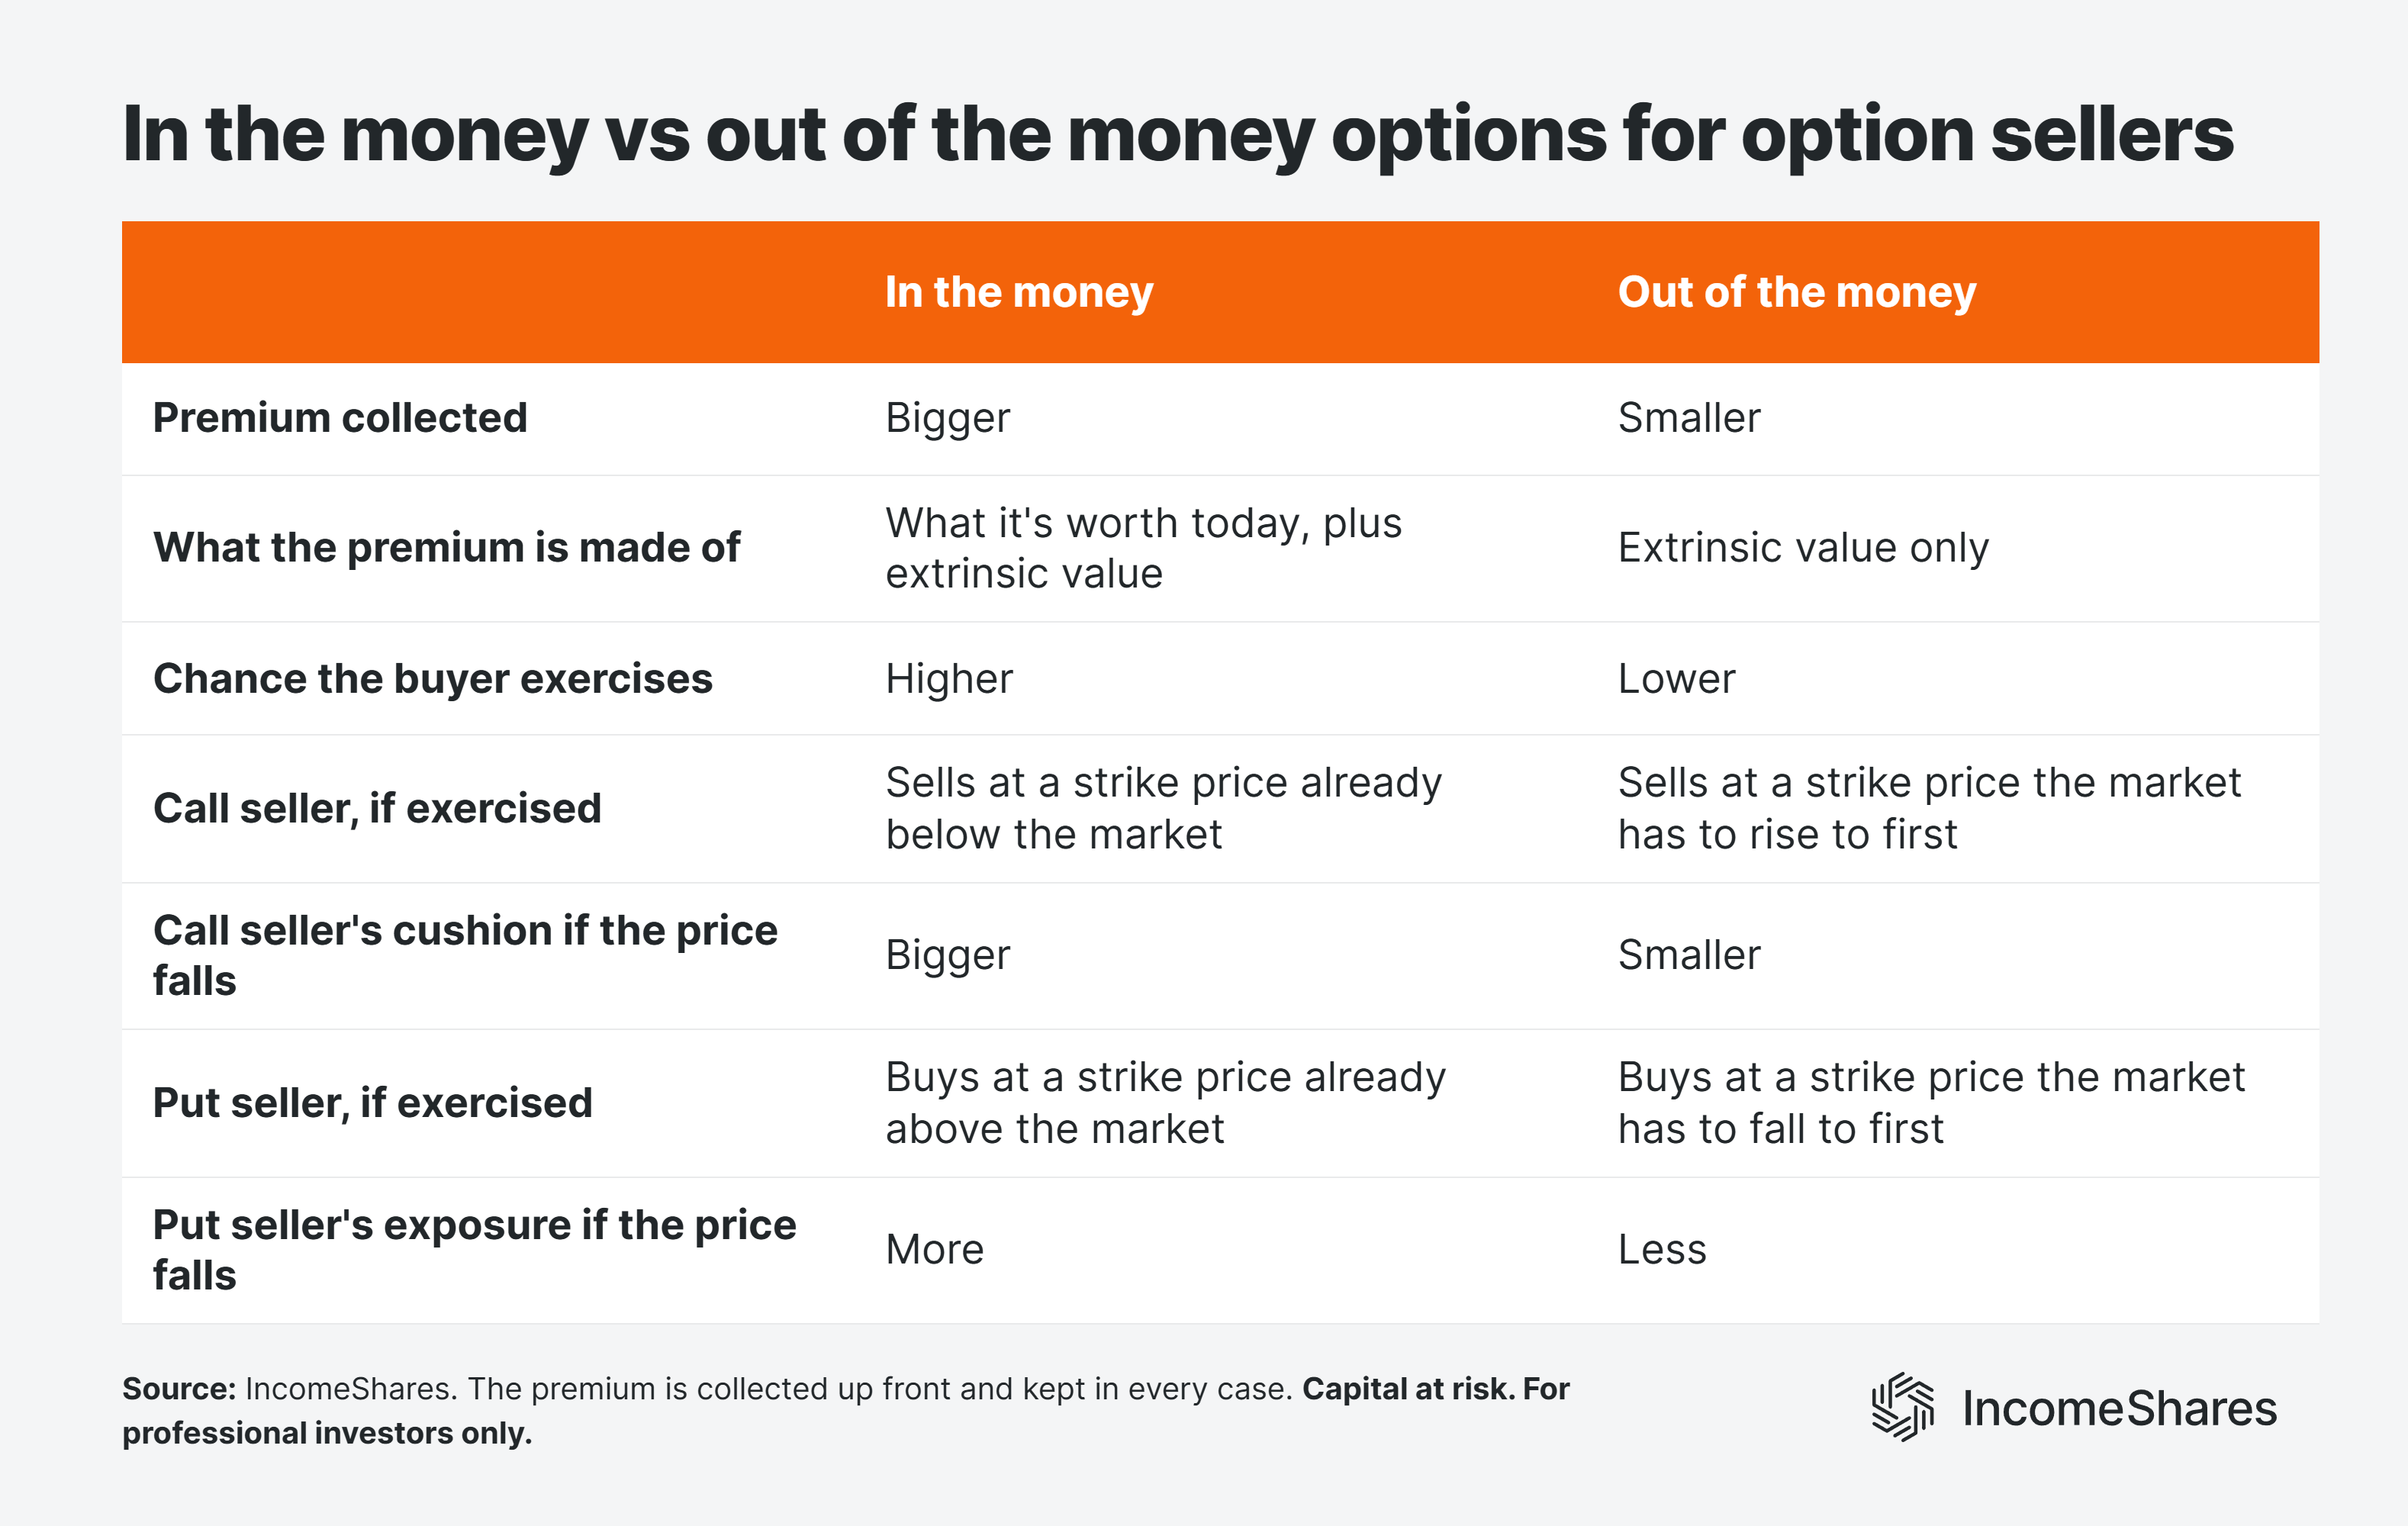
The table below sums up the differences for the seller.
IncomeShares ETPs use a mix of both. Our covered call ETPs currently sell out of the money calls on the asset they hold. Those are Gold+ Yield, Silver+ Yield, and 20+ Year Treasury Options. Our other ETPs currently sell puts, with strikes from out of the money to in the money. In every case, we collect the premium up front, and our monthly income distributions are paid from its extrinsic value.
Key highlights
An in the money option's premium is its intrinsic value (what it's worth today) plus extrinsic value (time value). An out of the money option's premium is all extrinsic value, so it's typically smaller.
Selling in the money pays more up front, but the buyer is more likely to exercise. Selling out of the money pays less, but you're more likely to keep your shares (calls) or your cash (puts).
The option seller keeps the premium either way. Which choice works out better depends on where the price goes – and nobody knows that in advance.
Your capital is at risk if you invest. You could lose all your investment. Please see the full risk warning here.
Related Products:

Strategy
Cash-Secured Put + Equity
Distribution Yield
49.98%

Strategy
Cash-Secured Put + Equity
Distribution Yield
39.21%

Strategy
Cash-Secured Put + Equity
Distribution Yield
119.40%

Strategy
Covered Call
Distribution Yield
12.73%

Strategy
Covered Call
Distribution Yield
12.20%